Taxation - May 2024
Official ICAI Suggested Answers — questions with model answers
Inside This Paper
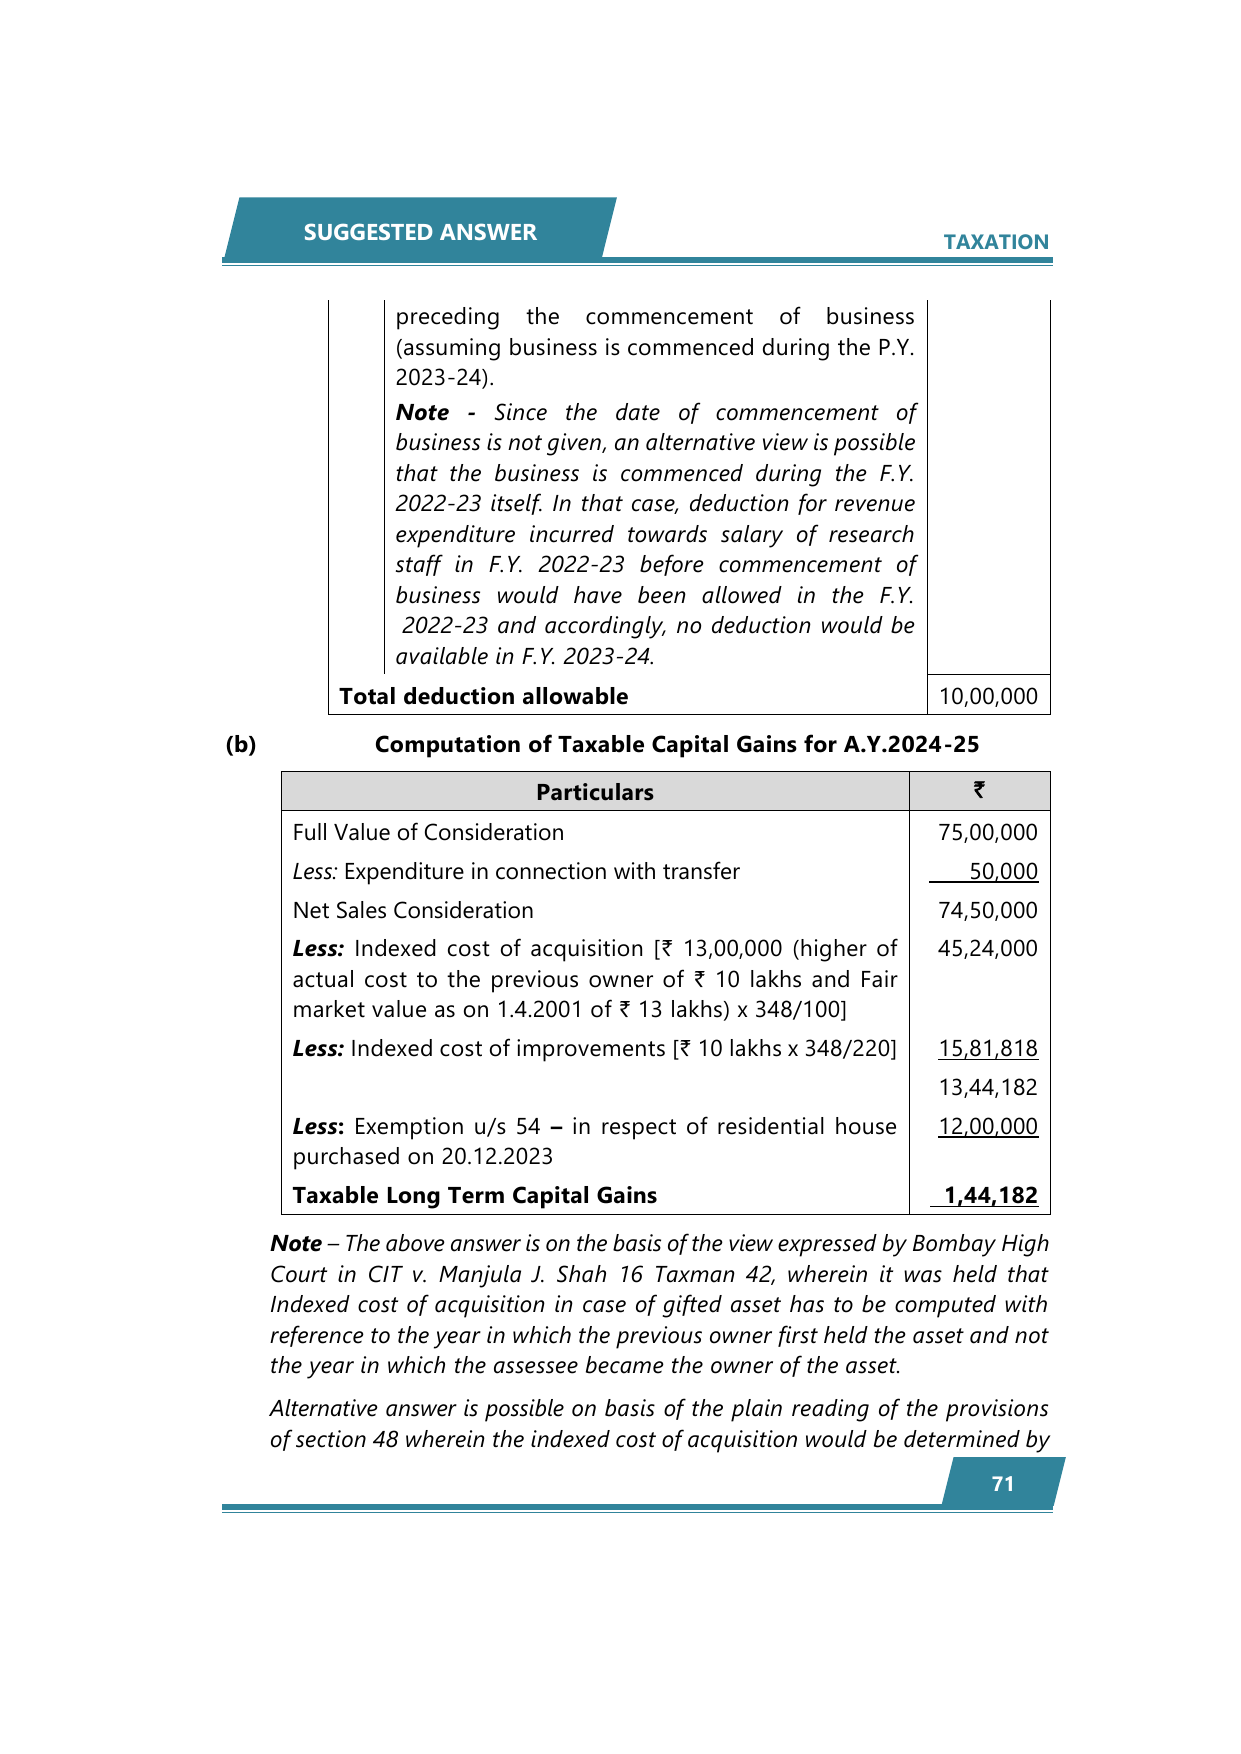
Mr. Sahil, resident Indian aged 40 years, a Manufacturer at Chennai, gives the following Manufacturing, Trading and Profit & Loss Account for the year ended 31.03.2024. Manufacturing, Trading and Profit & Loss Account for the year ended 31.03.2024 Particulars To Opening Stock 71,000 By Sales To Purchase of Raw Materials Particulars By Closing Stock 43,50,000 2,00,000 17,20,500 To Manufacturing Wages & Expenses 5,80,500 To Gross Profit 21,78,000 Total 45,50,000 Total To Administrative Charges To SGST Penalty Paid (It is not…
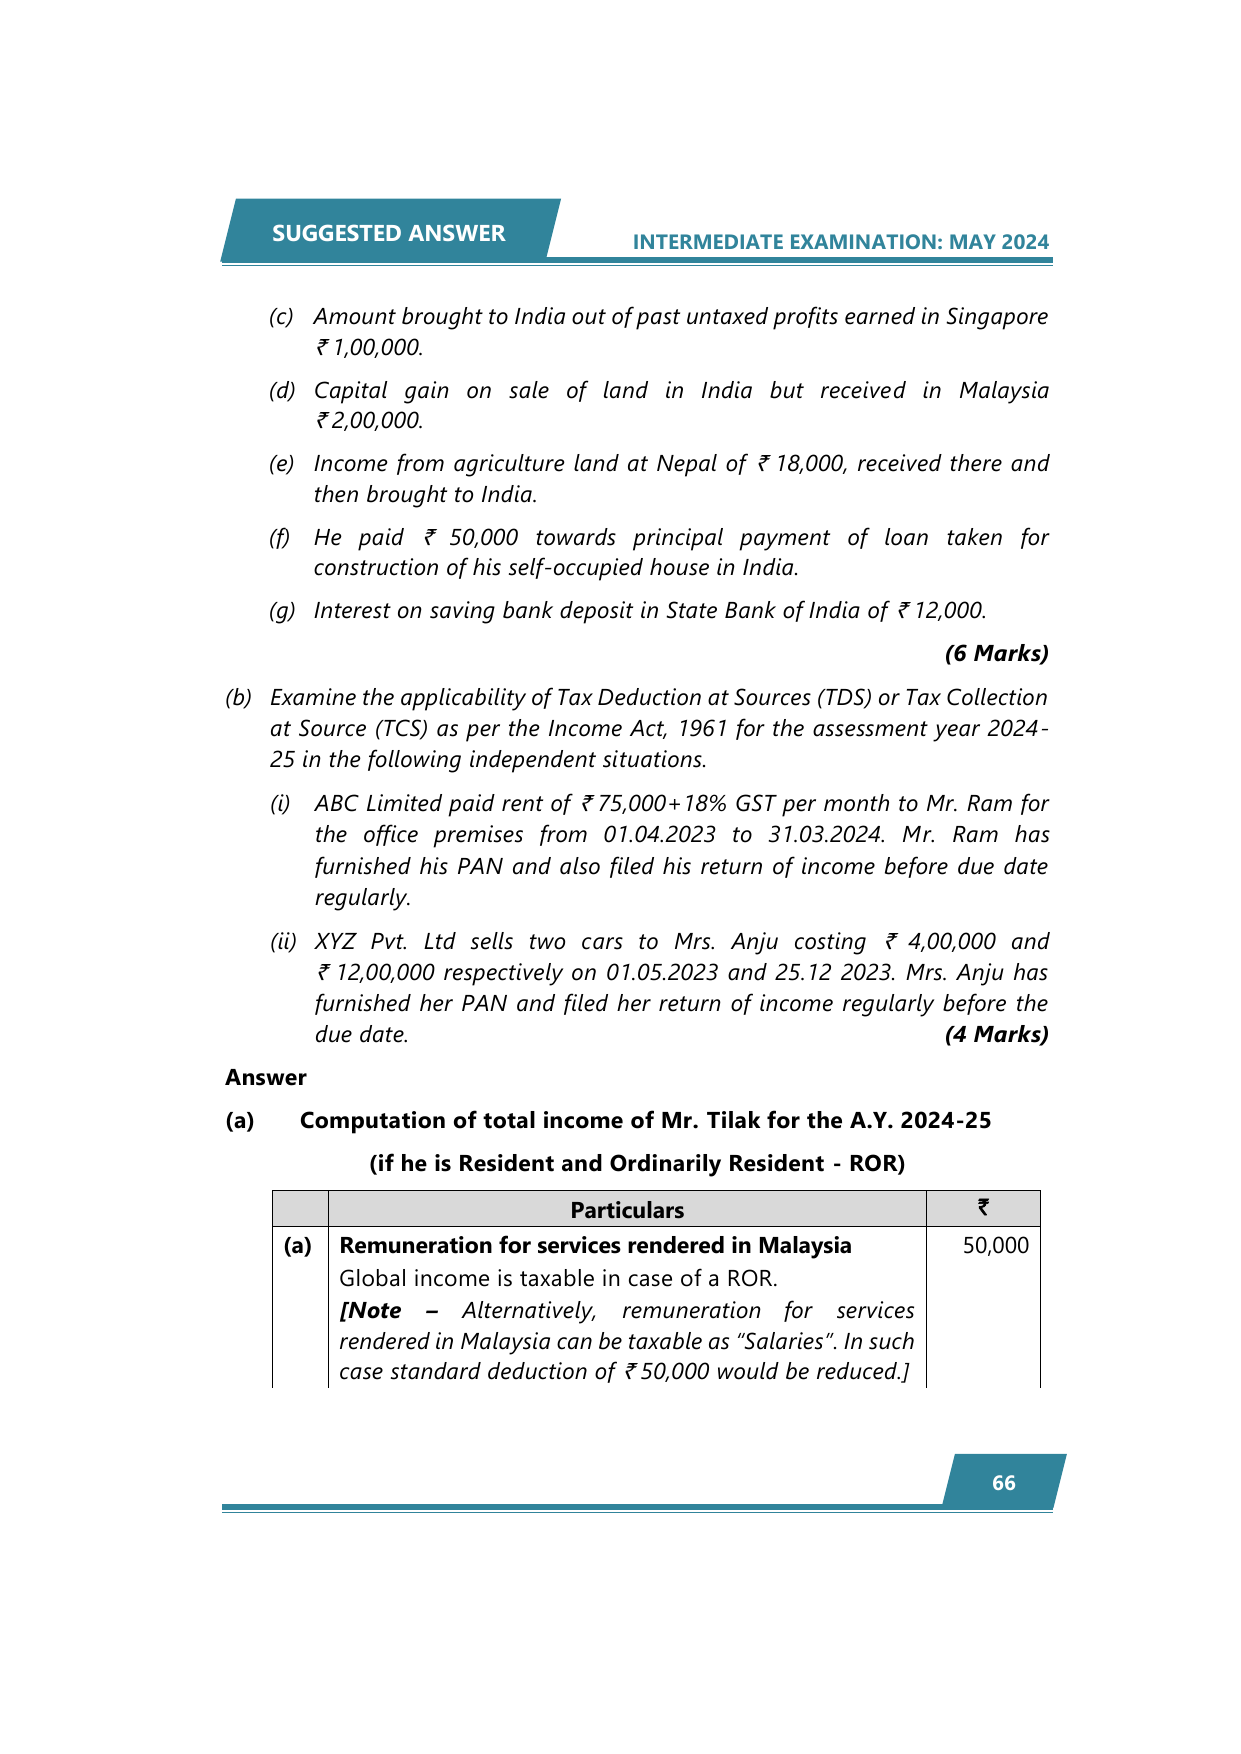
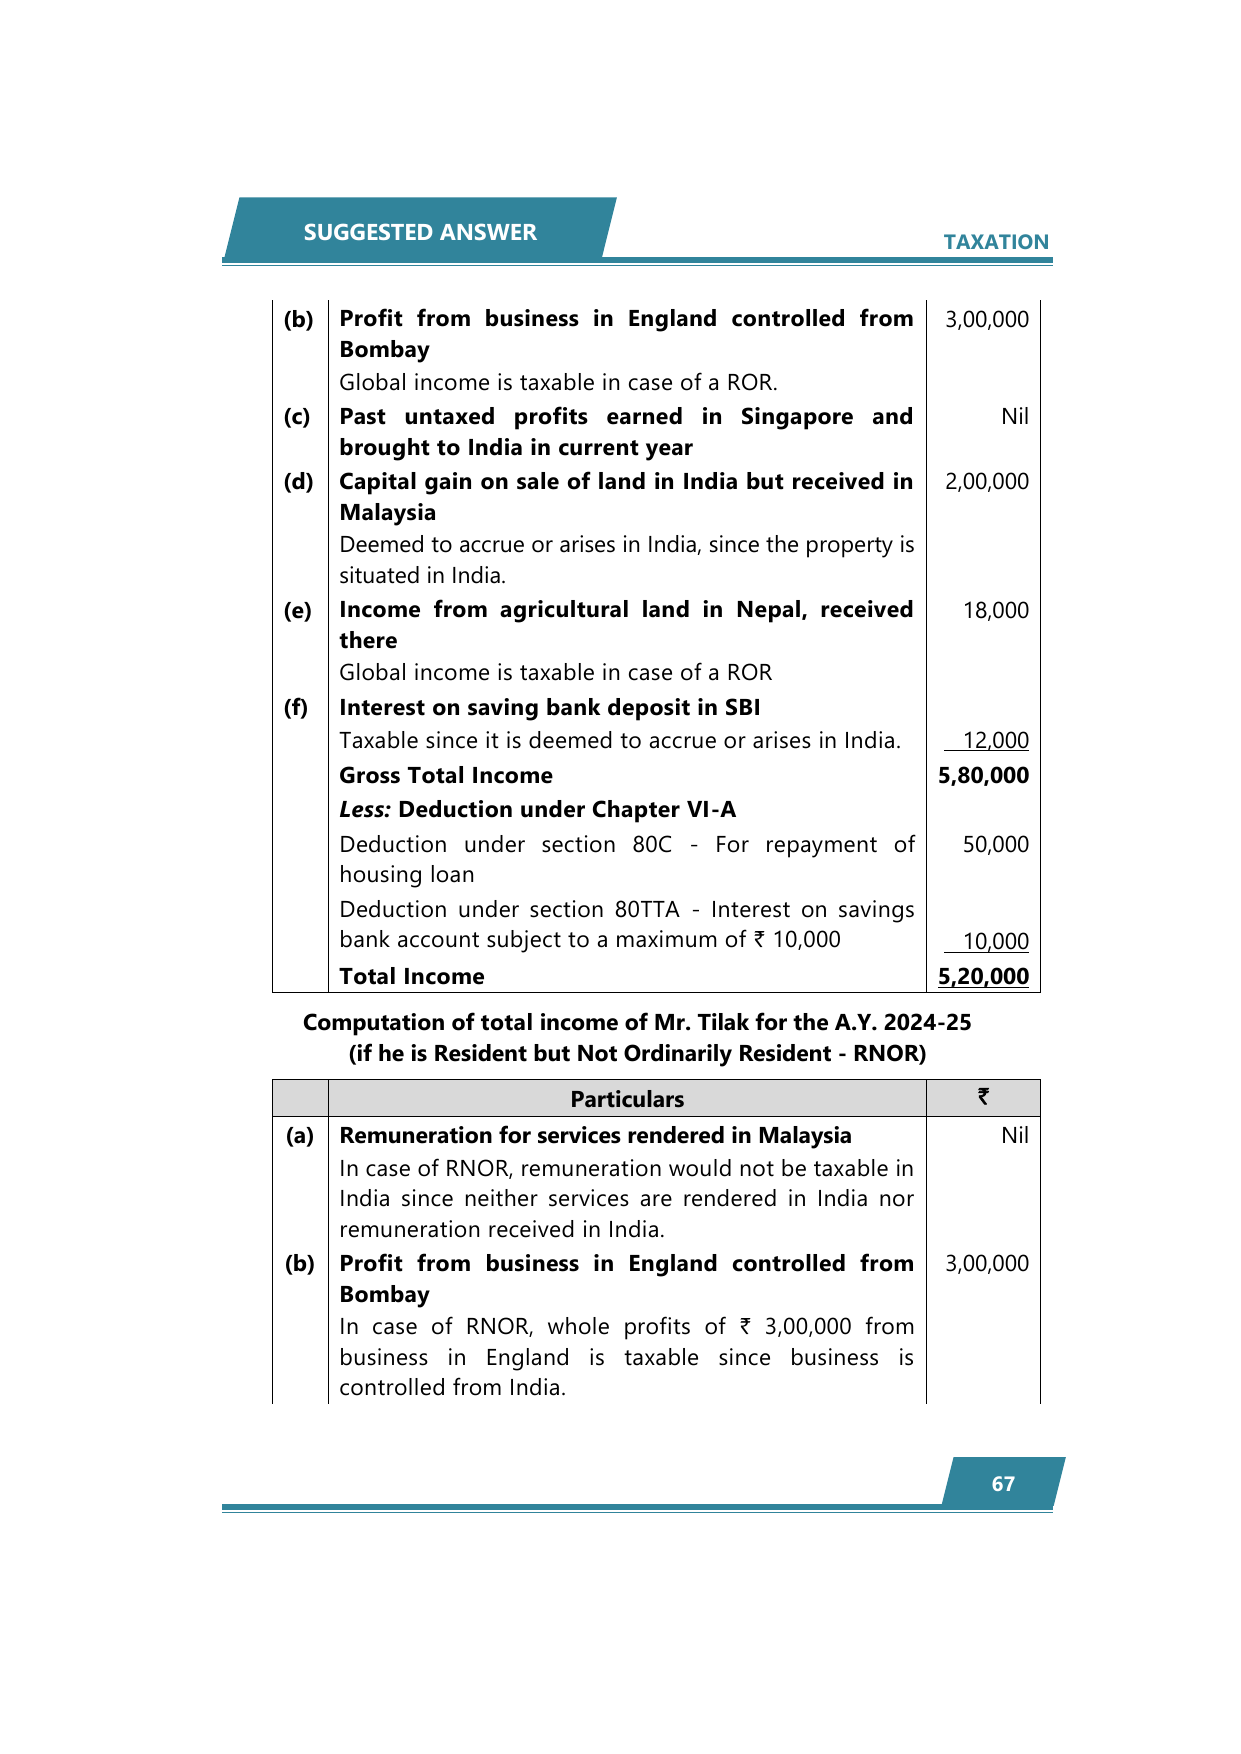
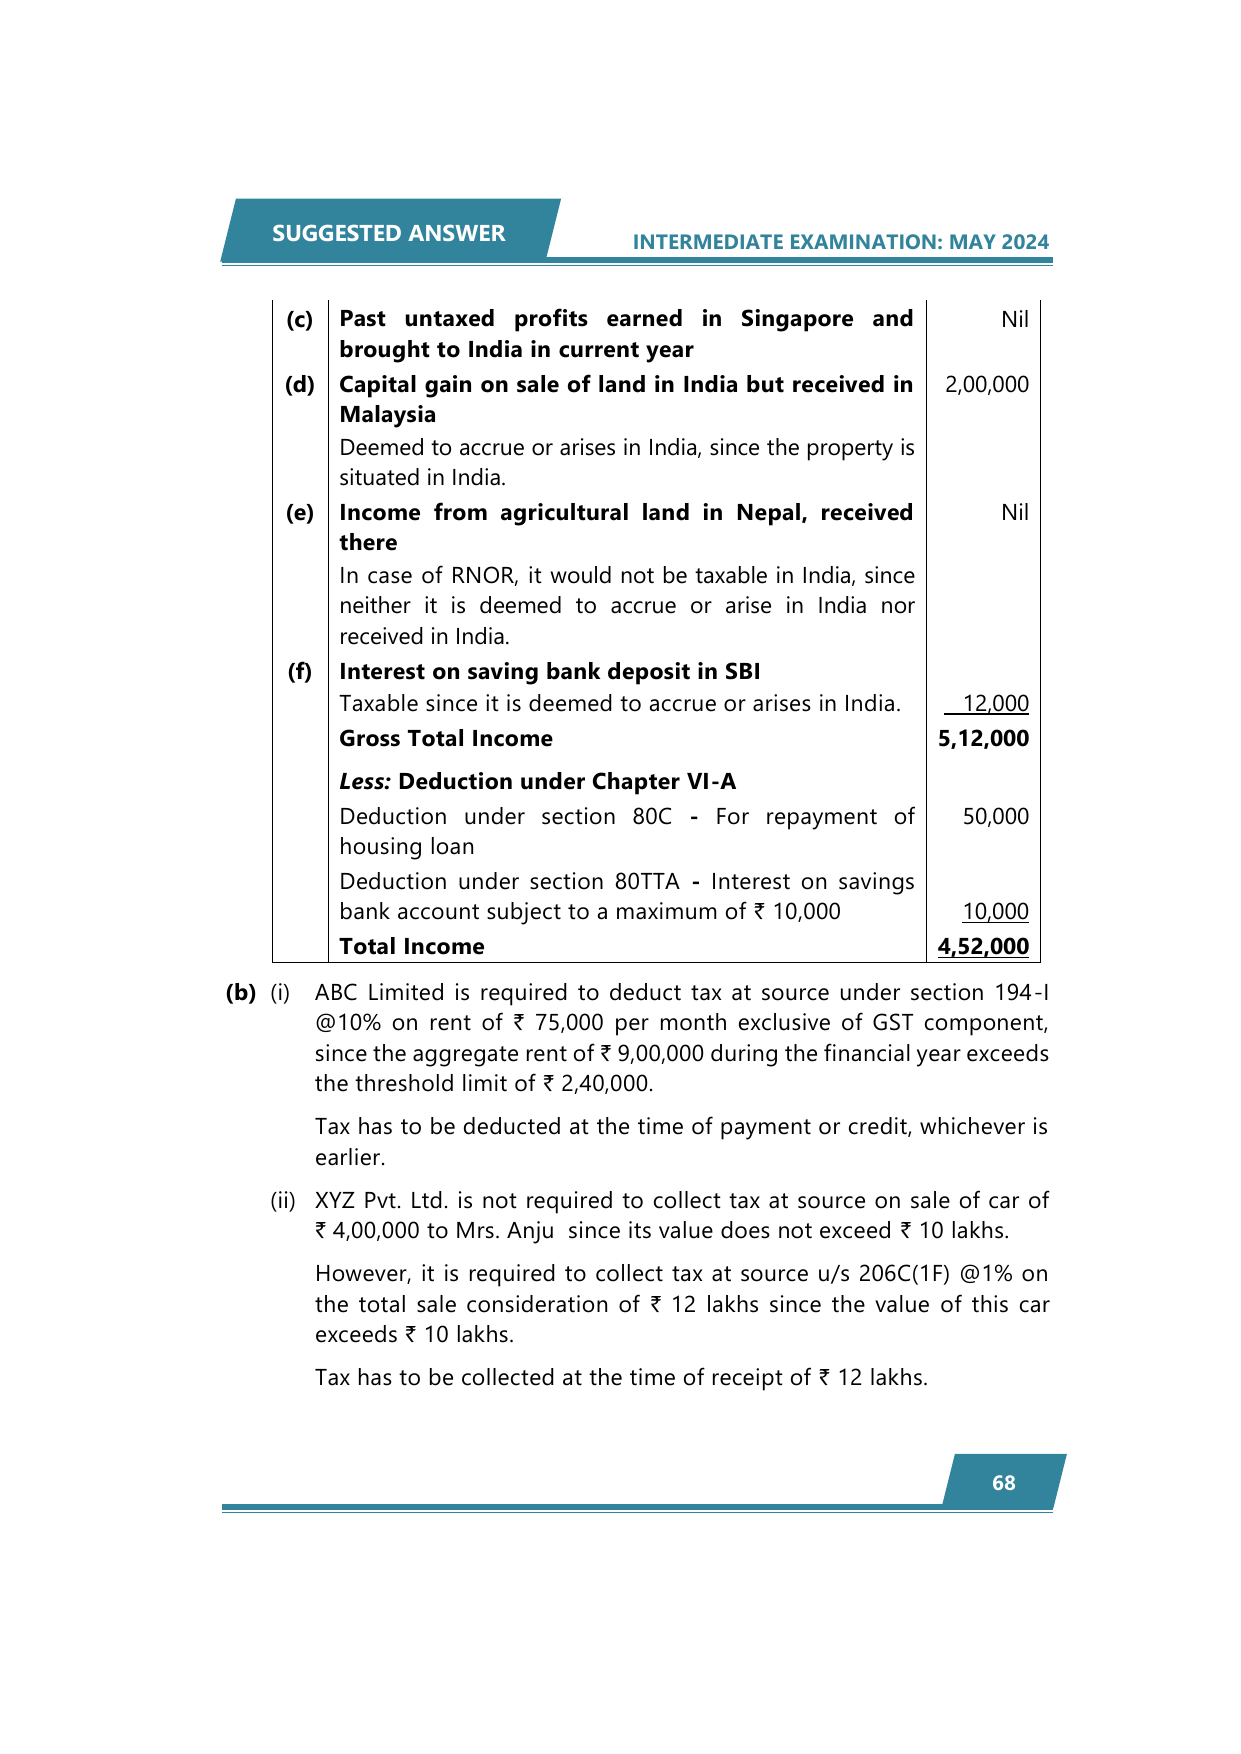
Mr. Tilak aged 35 years, furnishes the following information regarding his income for the assessment year 2024-25. Compute the total income if he is: (1) Resident and Ordinarily Resident. (2) Resident but Not Ordinarily Resident (Ignore the provisions of Section 115BAC). (a) Remuneration of ` 50,000 for service rendered in Malaysia, credited to his bank account in Malaysia and immediately remitted to his bank account in India. (b) Profits from a business in England controlled from Bombay ` 3,00,000 (out…
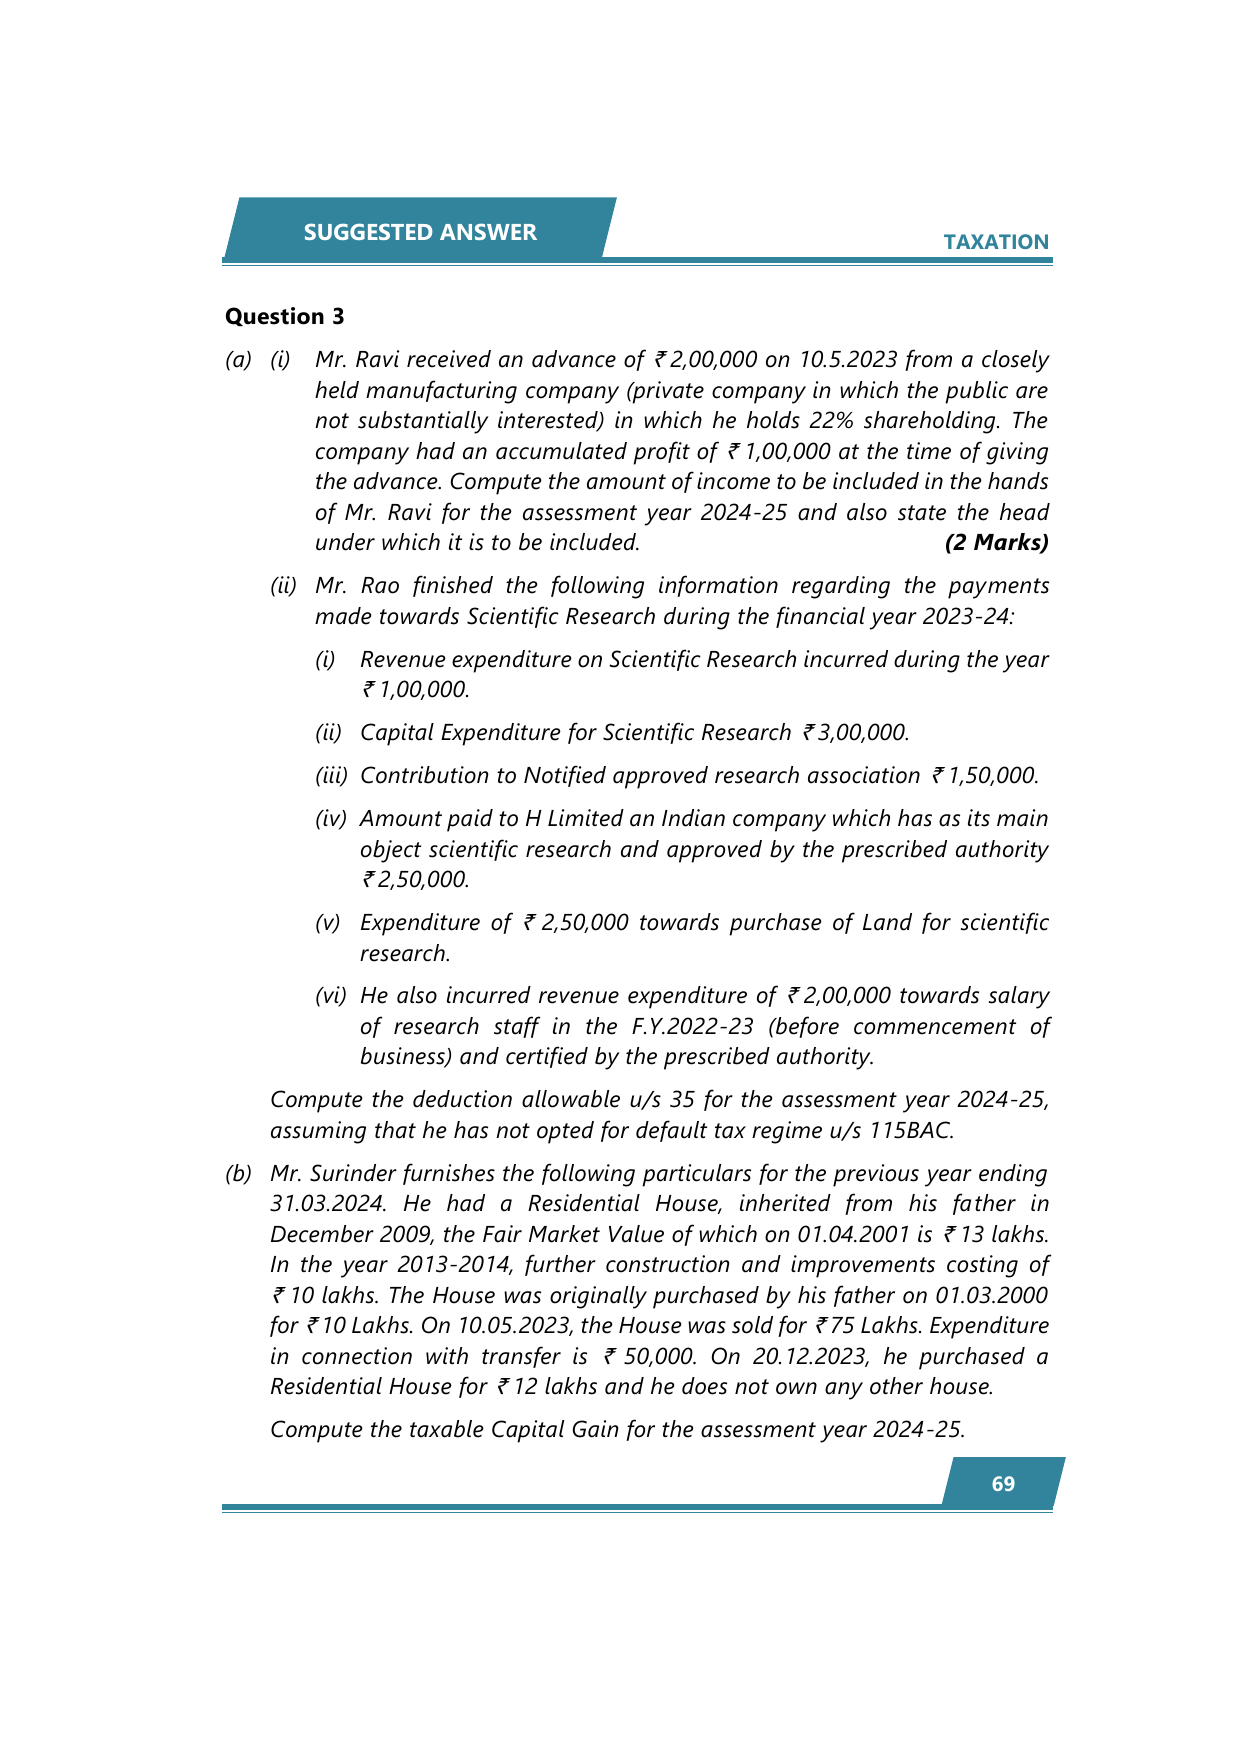
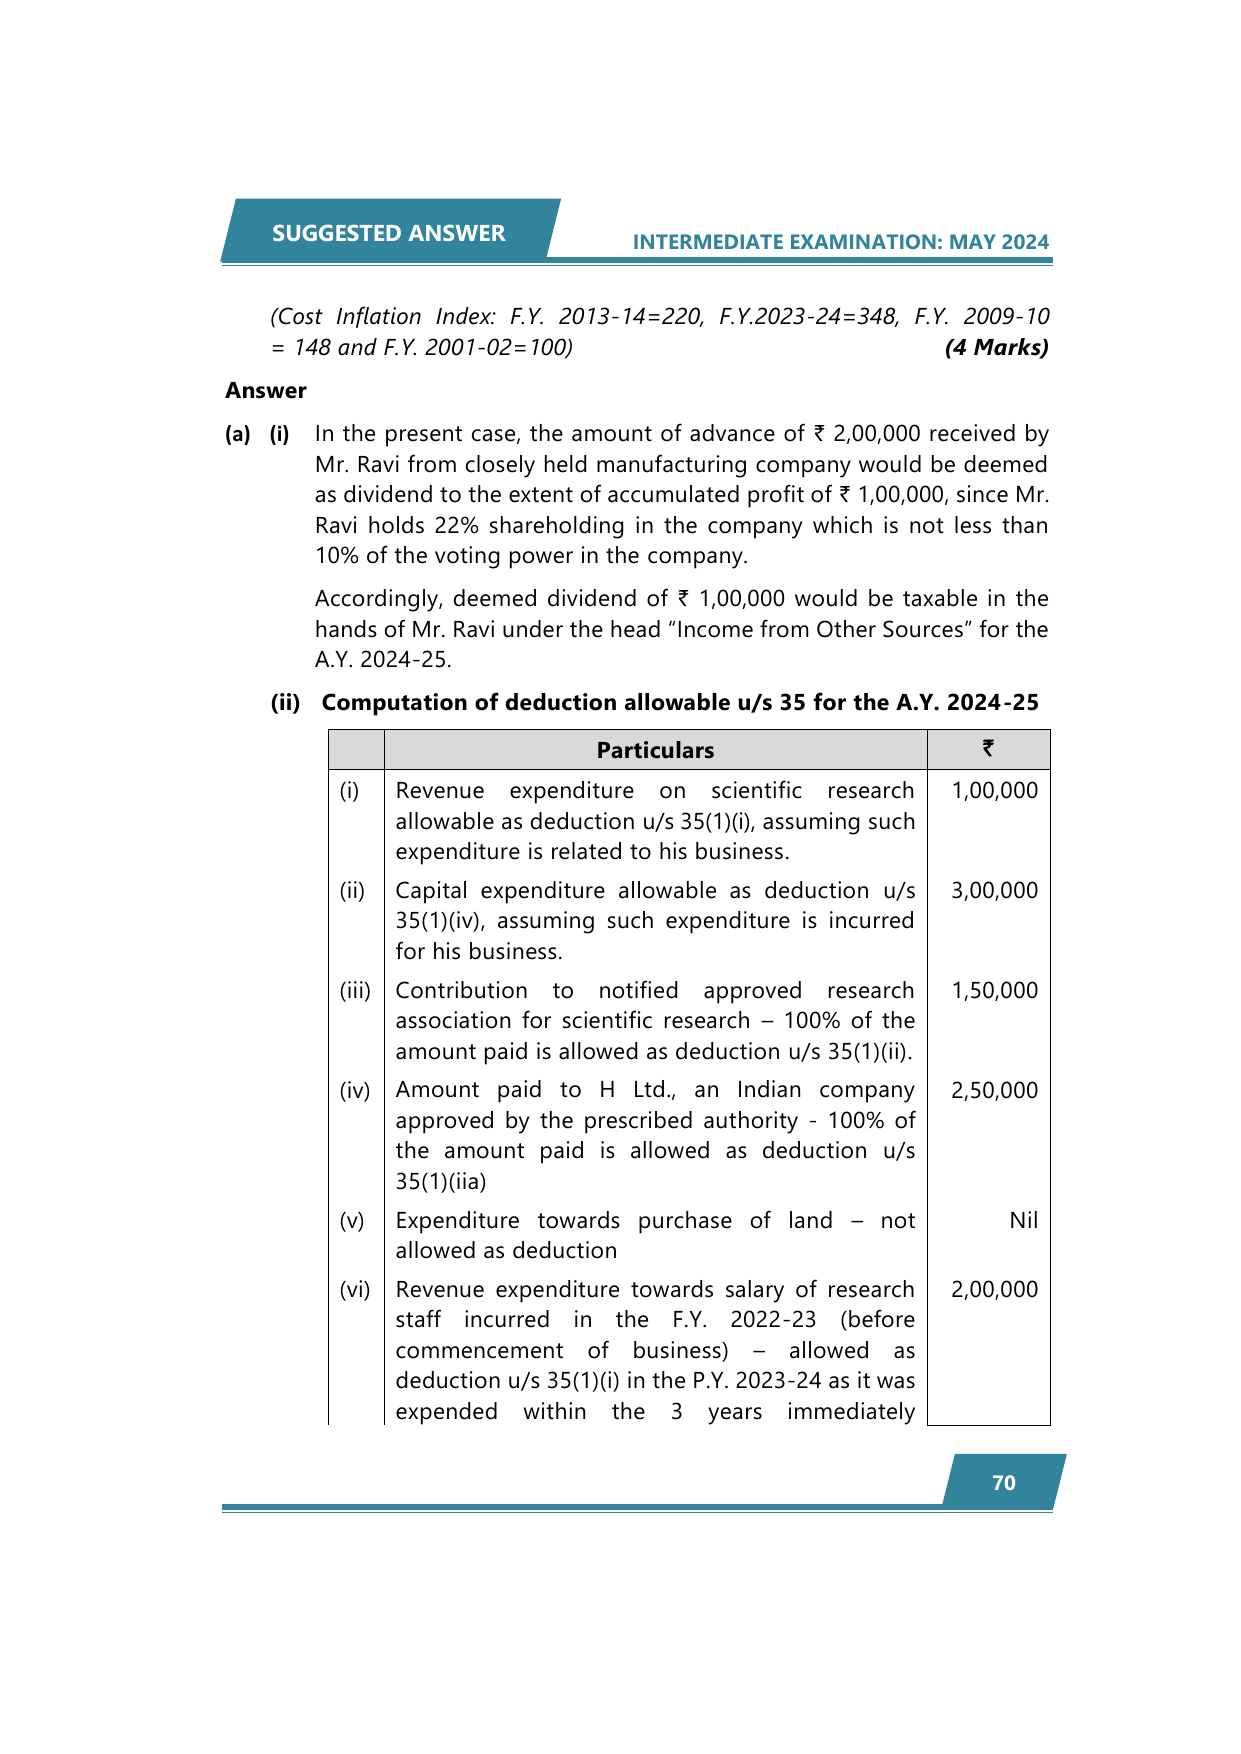
Mr. Ravi received an advance of ` 2,00,000 on 10.5.2023 from a closely held manufacturing company (private company in which the public are not substantially interested) in which he holds 22% shareholding. The company had an accumulated profit of ` 1,00,000 at the time of giving the advance. Compute the amount of income to be included in the hands of Mr. Ravi for the assessment year 2024-25 and also state the head under which it is to be included. (2…
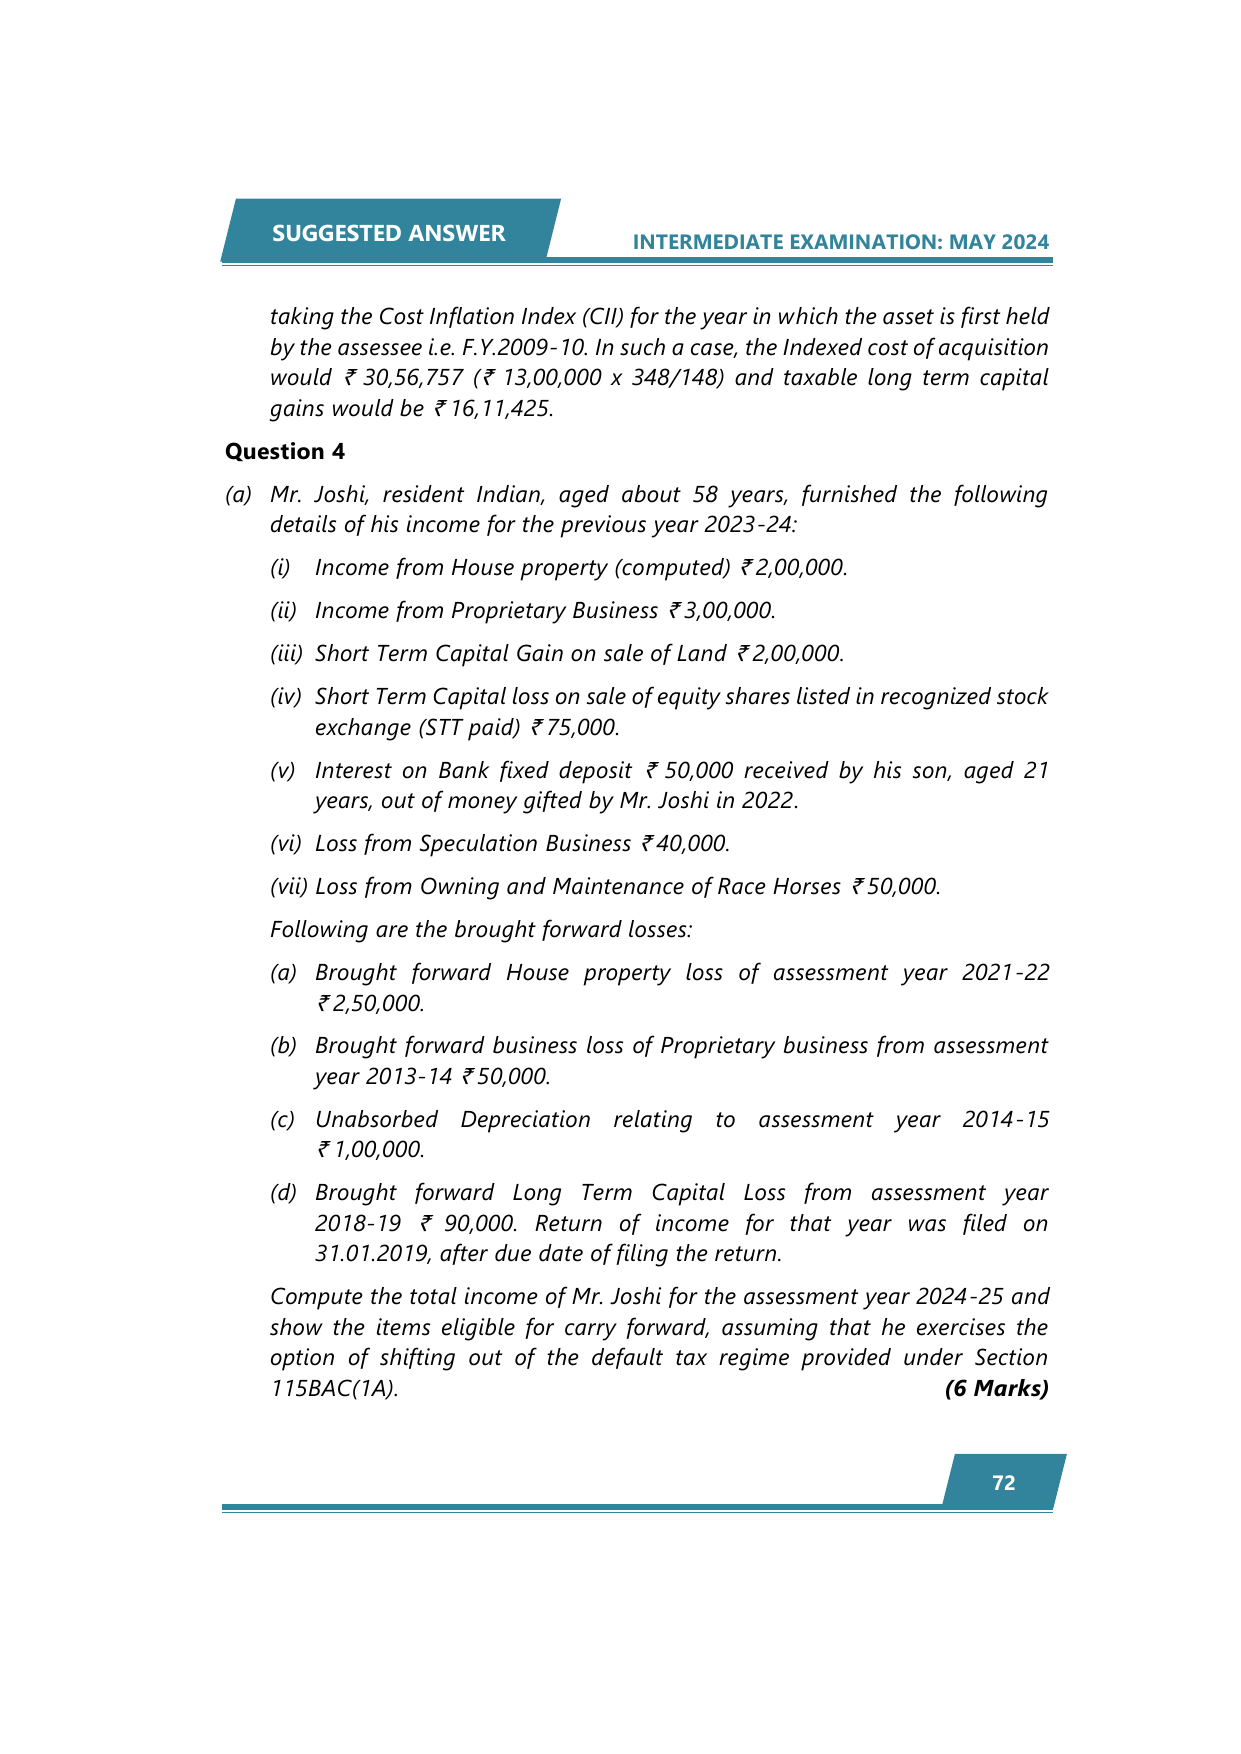
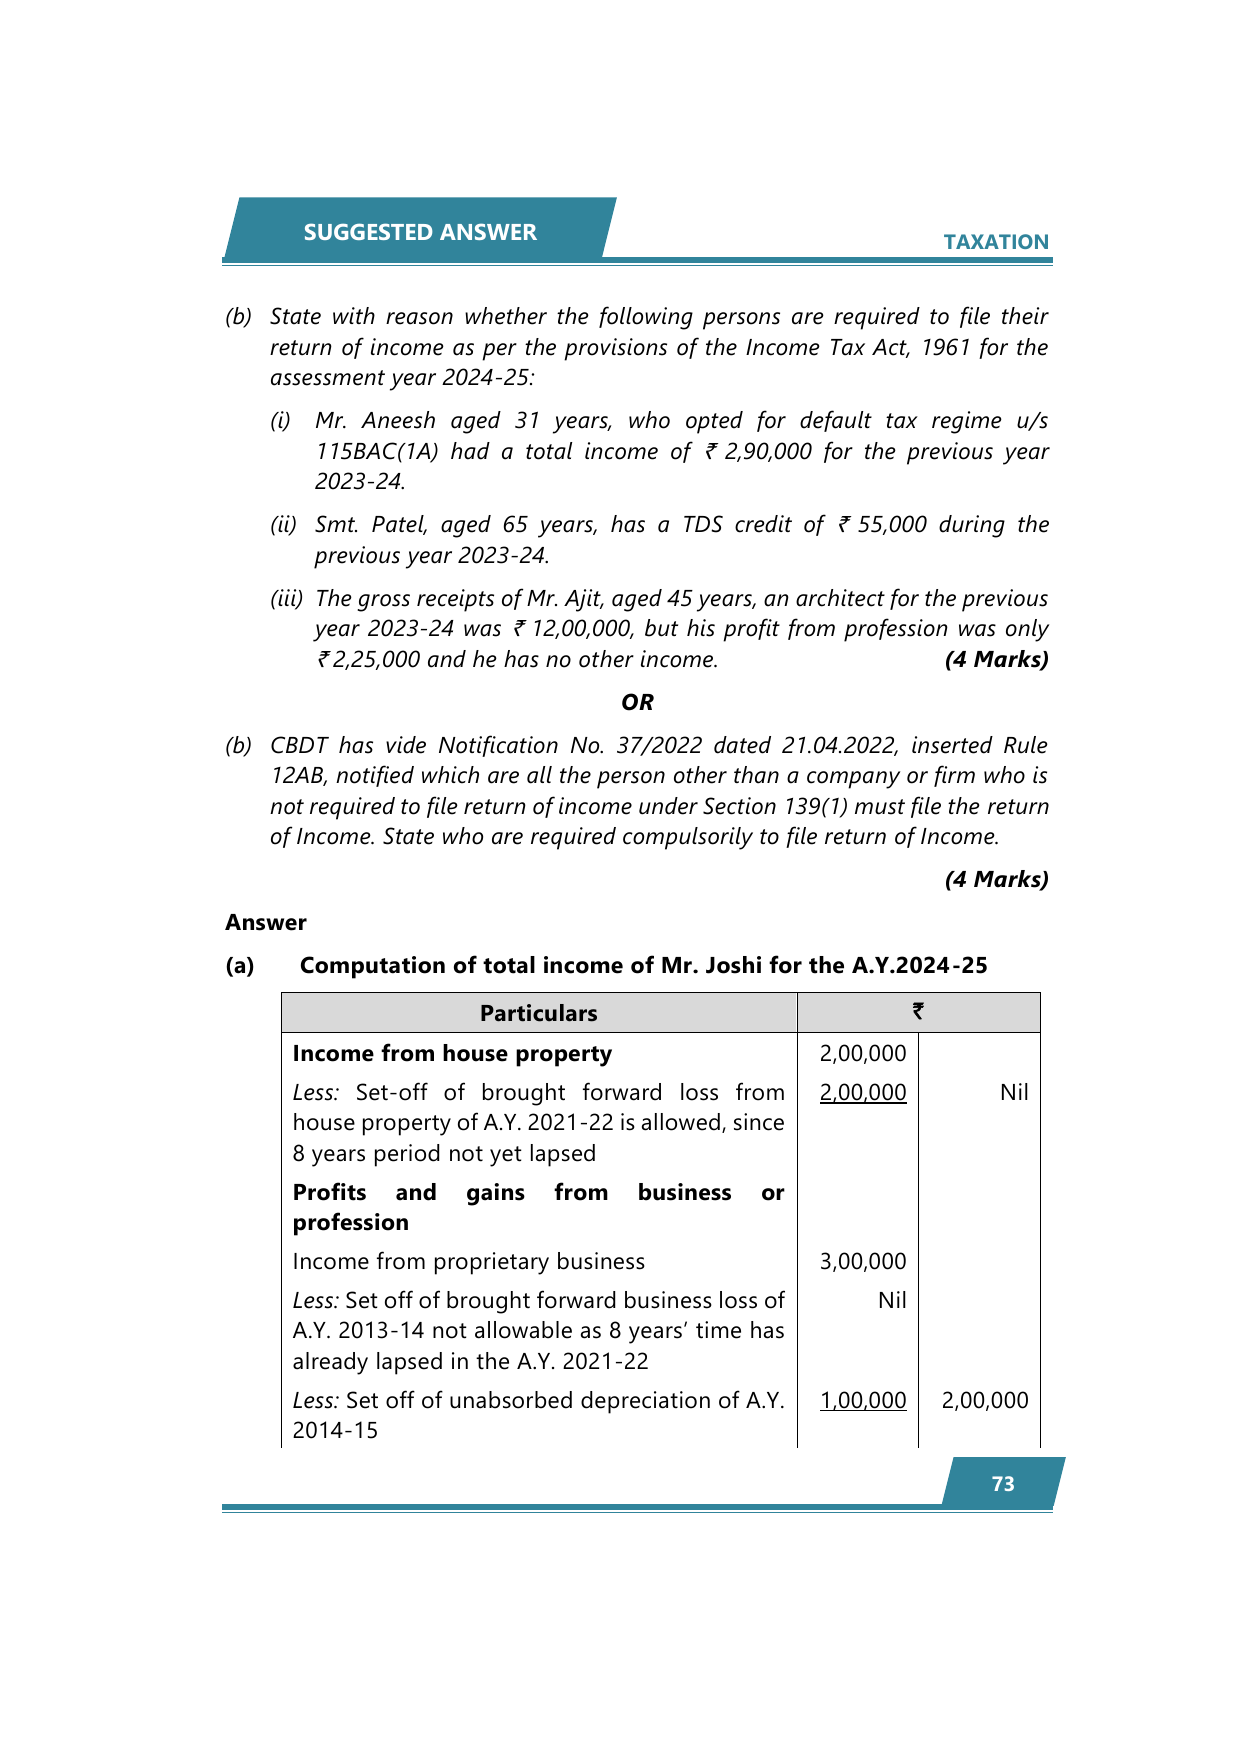
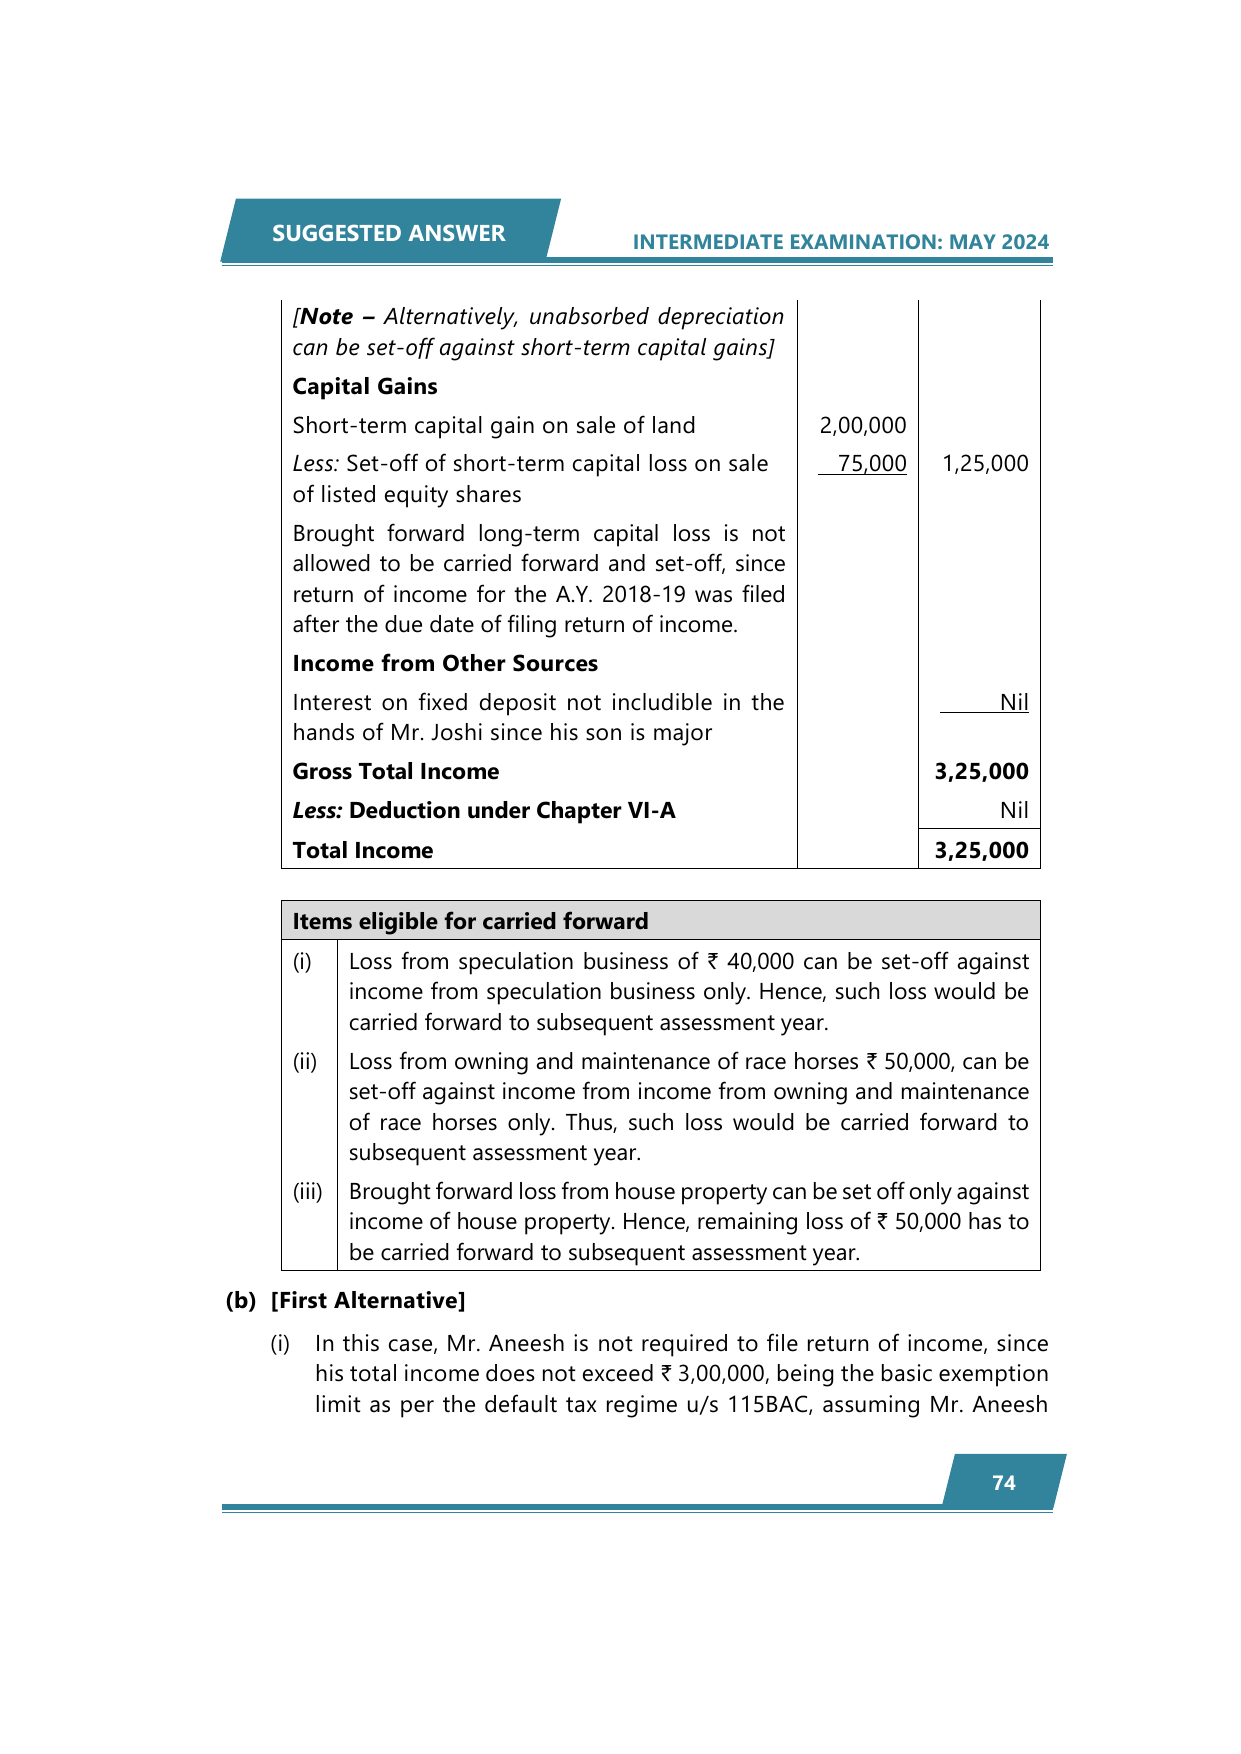
Mr. Joshi, resident Indian, aged about 58 years, furnished the following details of his income for the previous year 2023-24: (i) Income from House property (computed) ` 2,00,000. (ii) Income from Proprietary Business ` 3,00,000. (iii) Short Term Capital Gain on sale of Land ` 2,00,000. (iv) Short Term Capital loss on sale of equity shares listed in recognized stock exchange (STT paid) ` 75,000. (v) Interest on Bank fixed deposit ` 50,000 received by his son, aged 21 years…
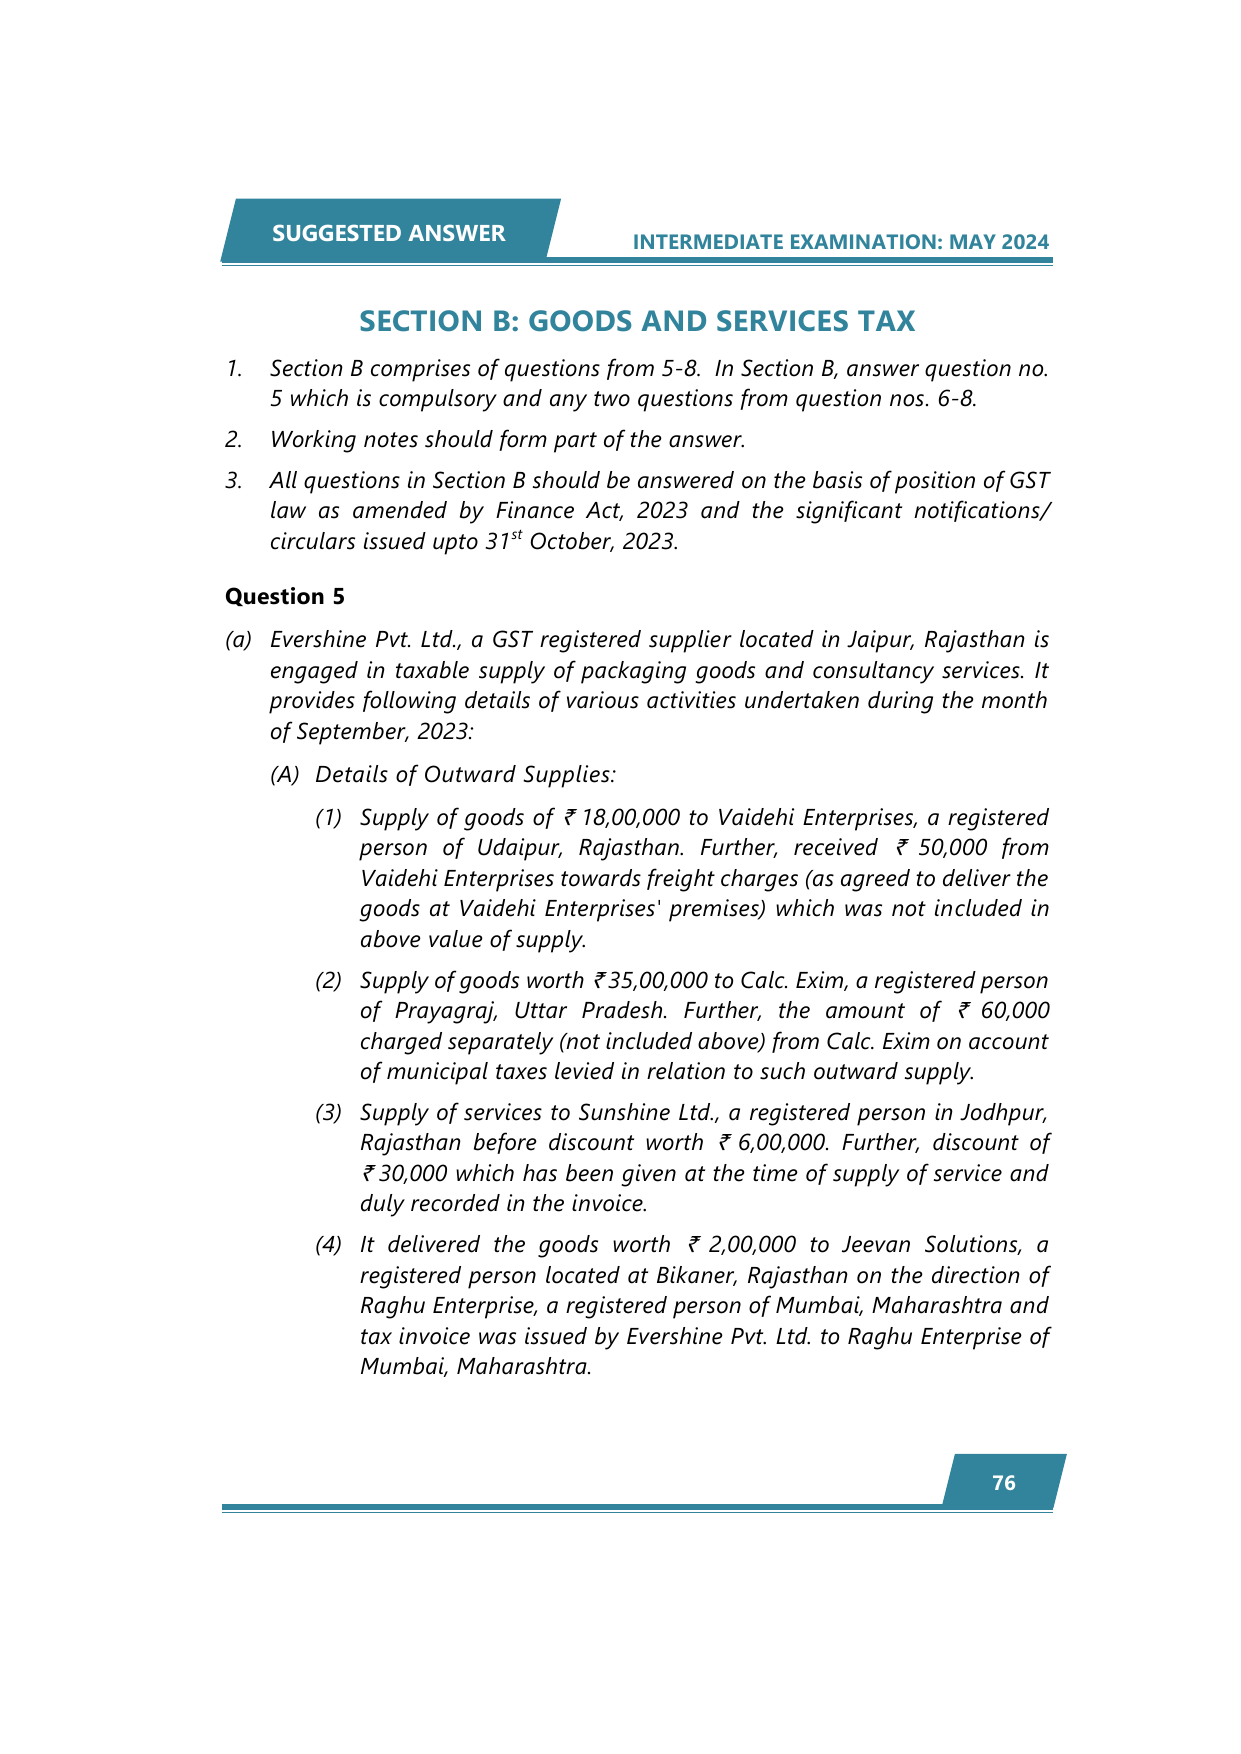
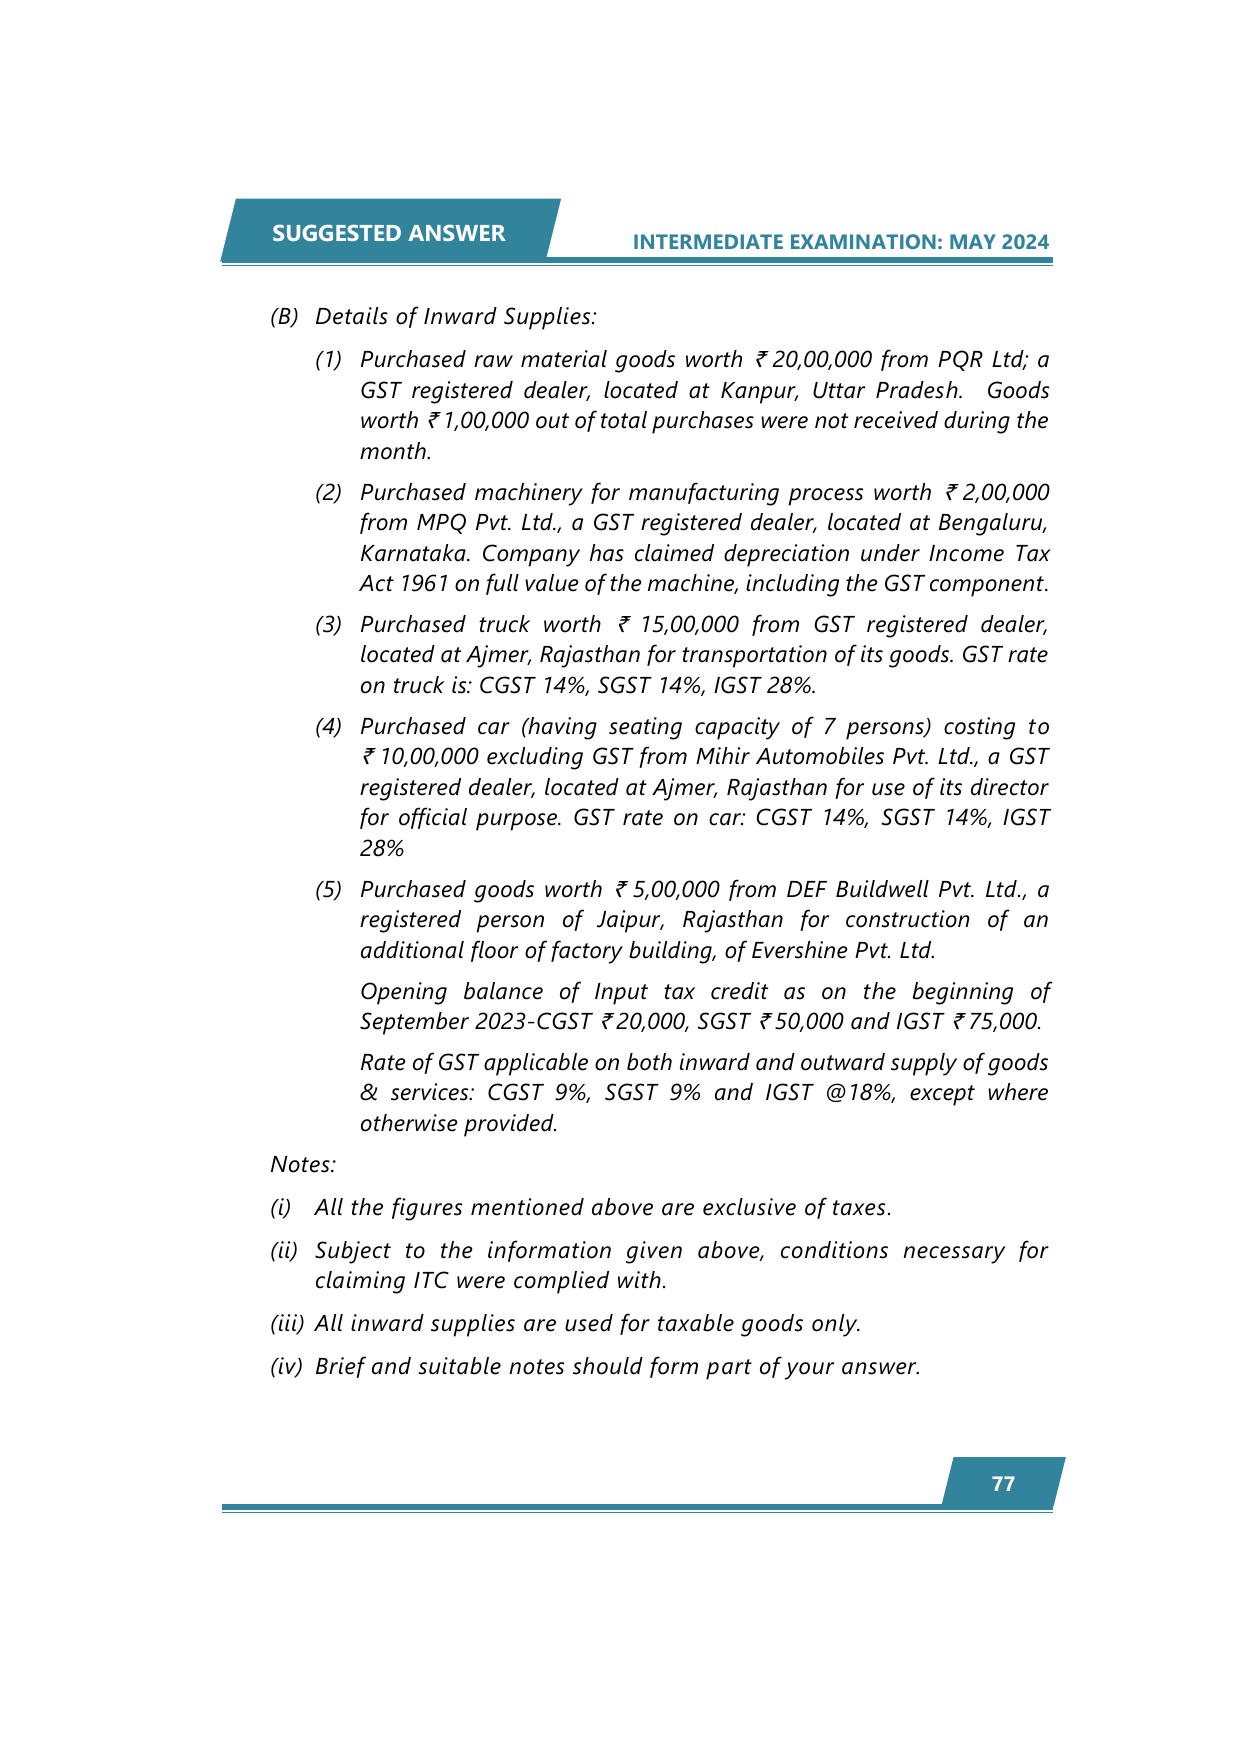
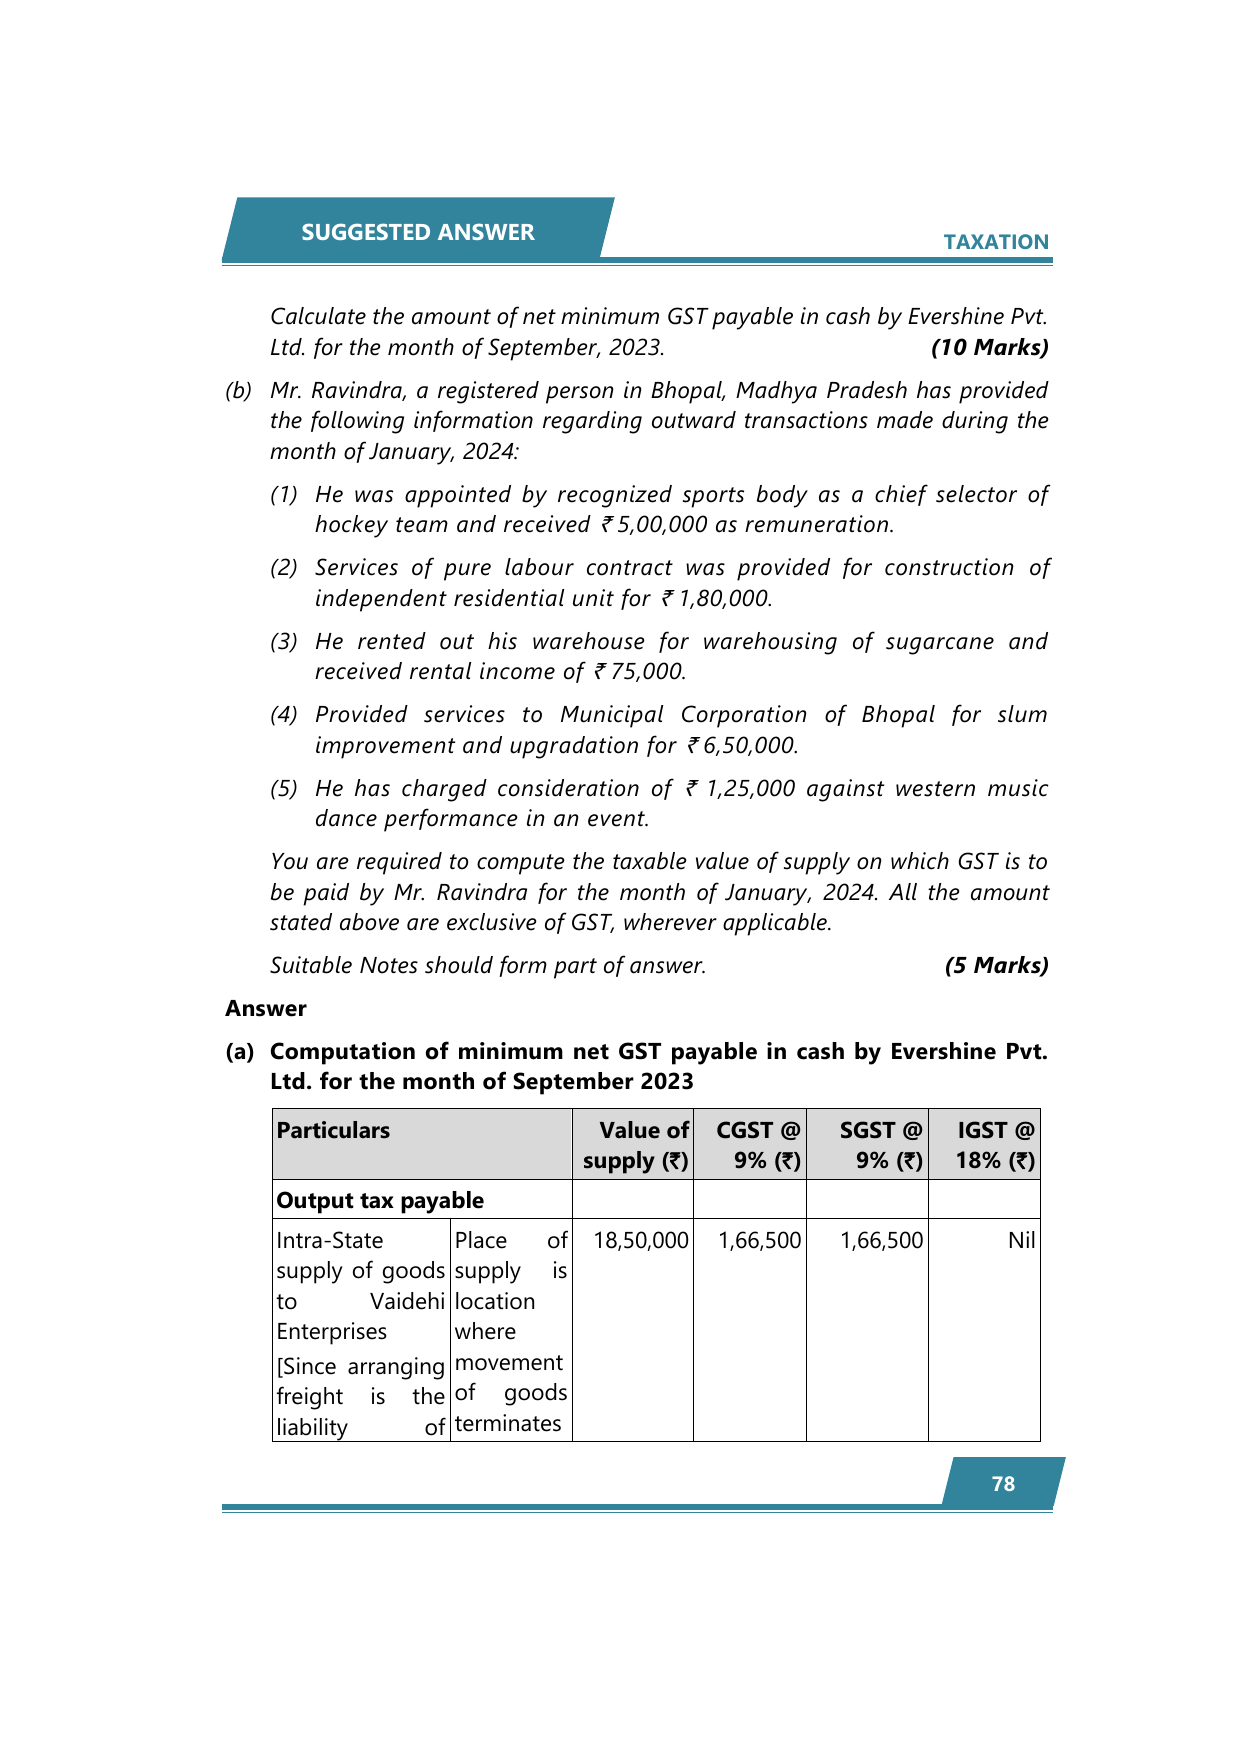
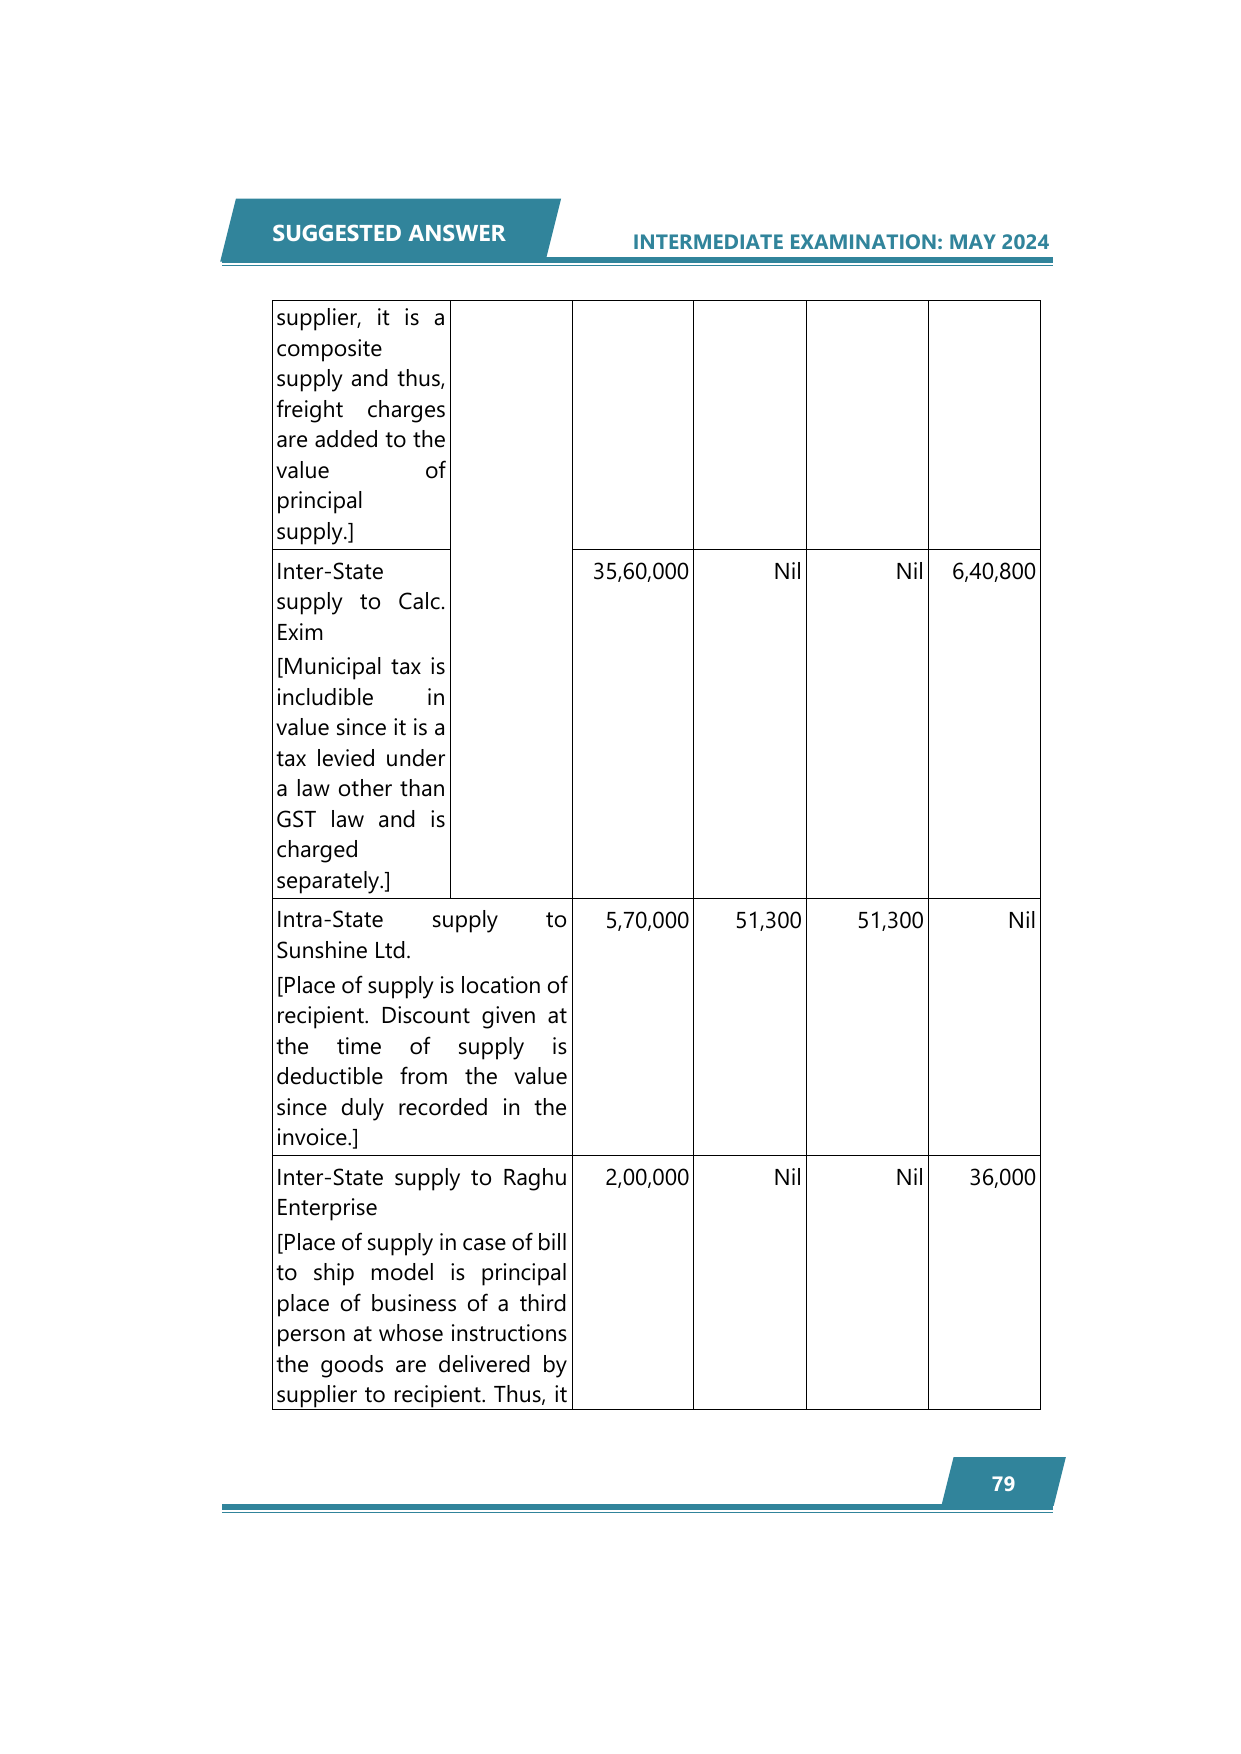
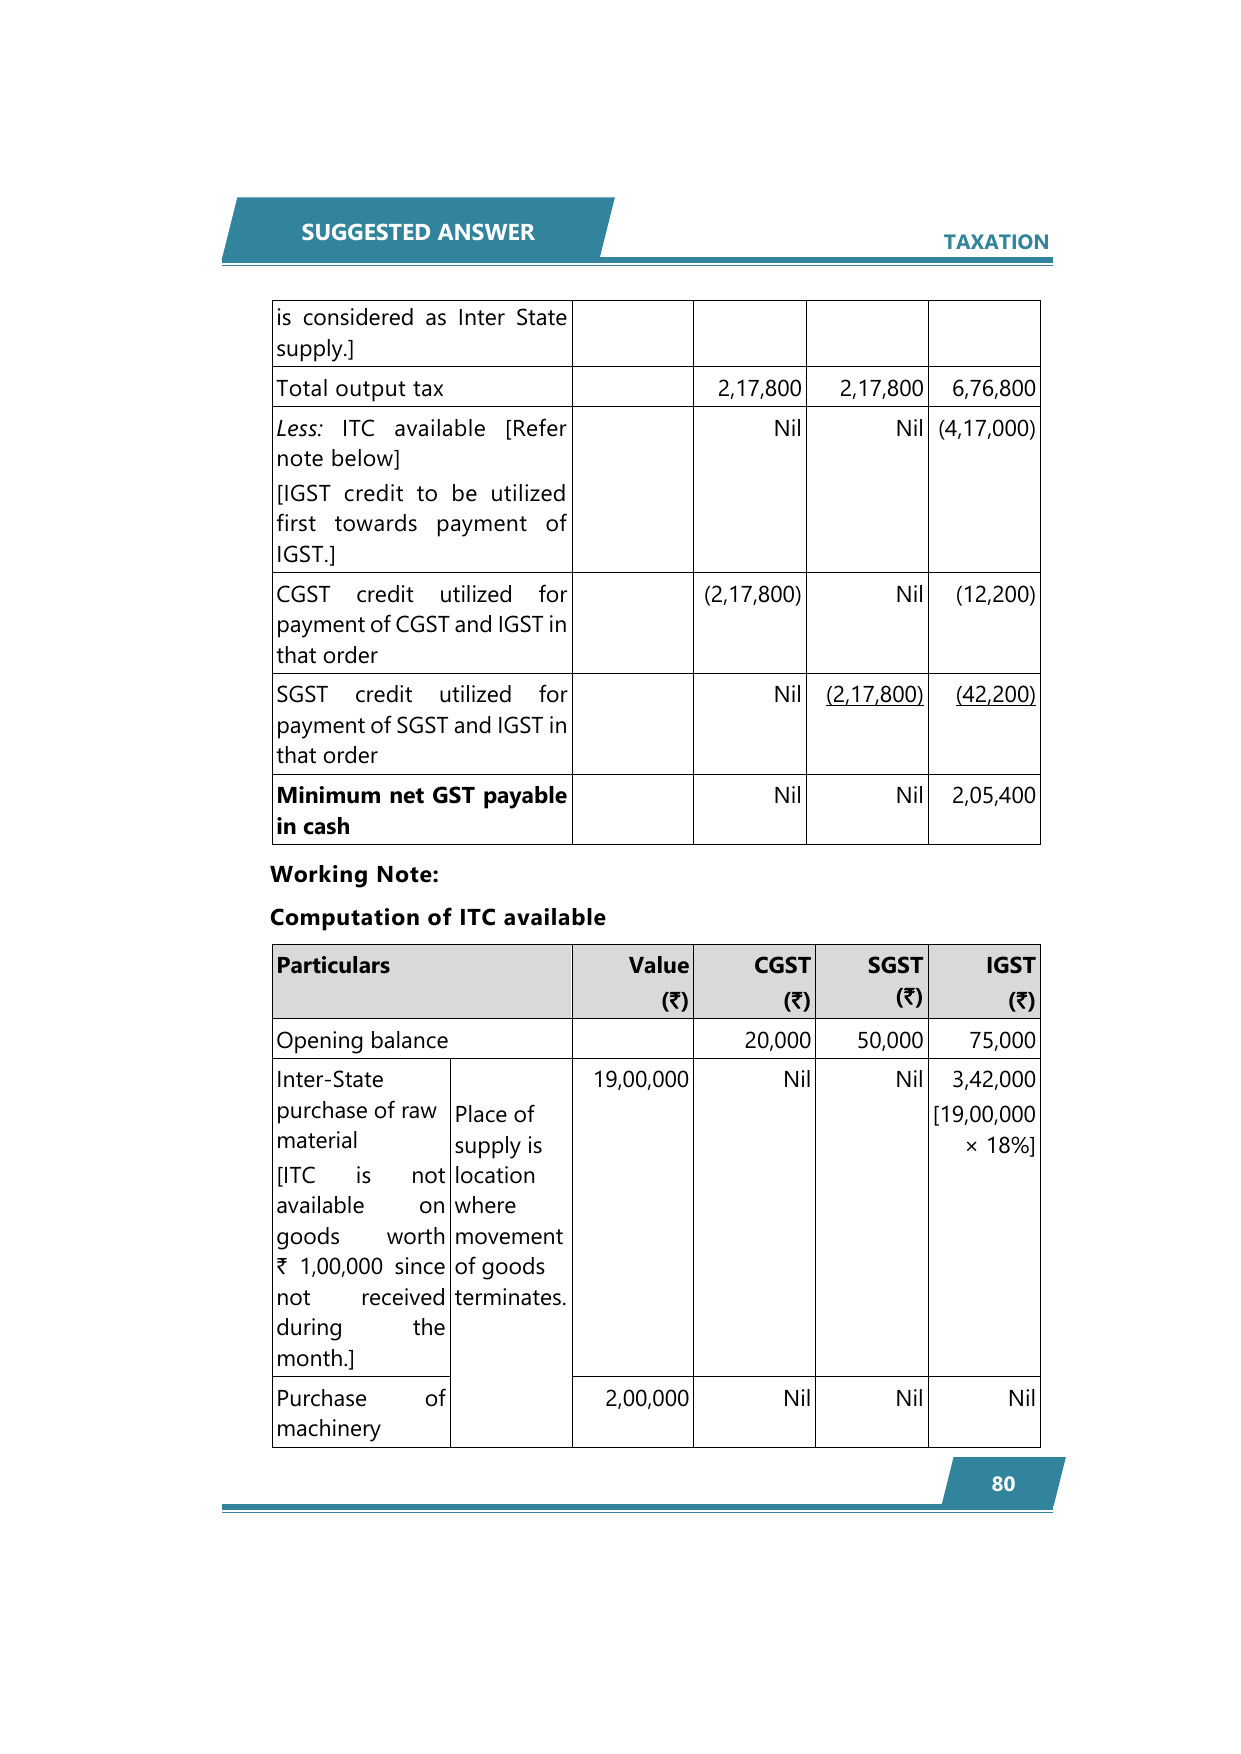
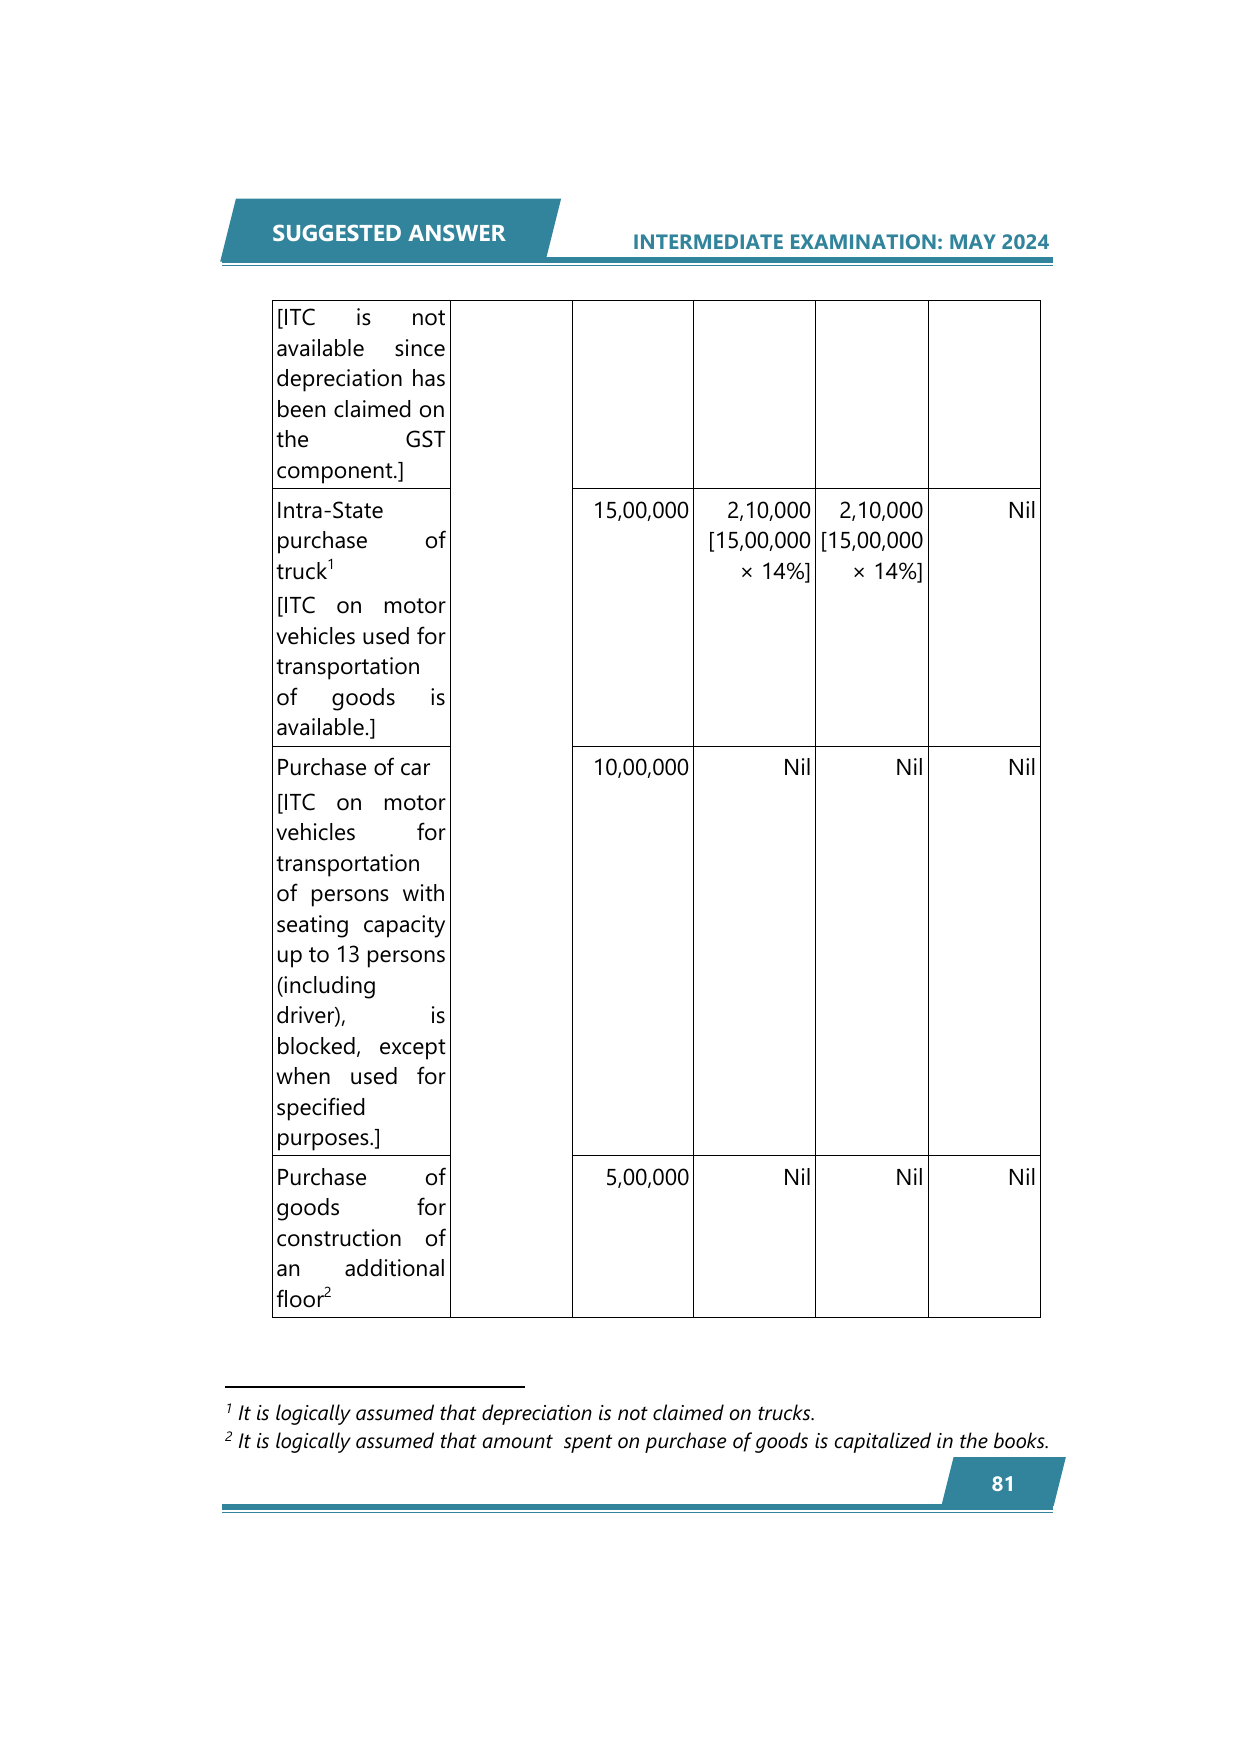
Pvt. Ltd., a GST registered supplier located in Jaipur, Rajasthan is engaged in taxable supply of packaging goods and consultancy services. It provides following details of various activities undertaken during the month of September, 2023: (A) Details of Outward Supplies: (1) Supply of goods of ` 18,00,000 to Vaidehi Enterprises, a registered person of Udaipur, Rajasthan. Further, received ` 50,000 from Vaidehi Enterprises towards freight charges (as agreed to deliver the goods at Vaidehi Enterprises' premises) which was not included…
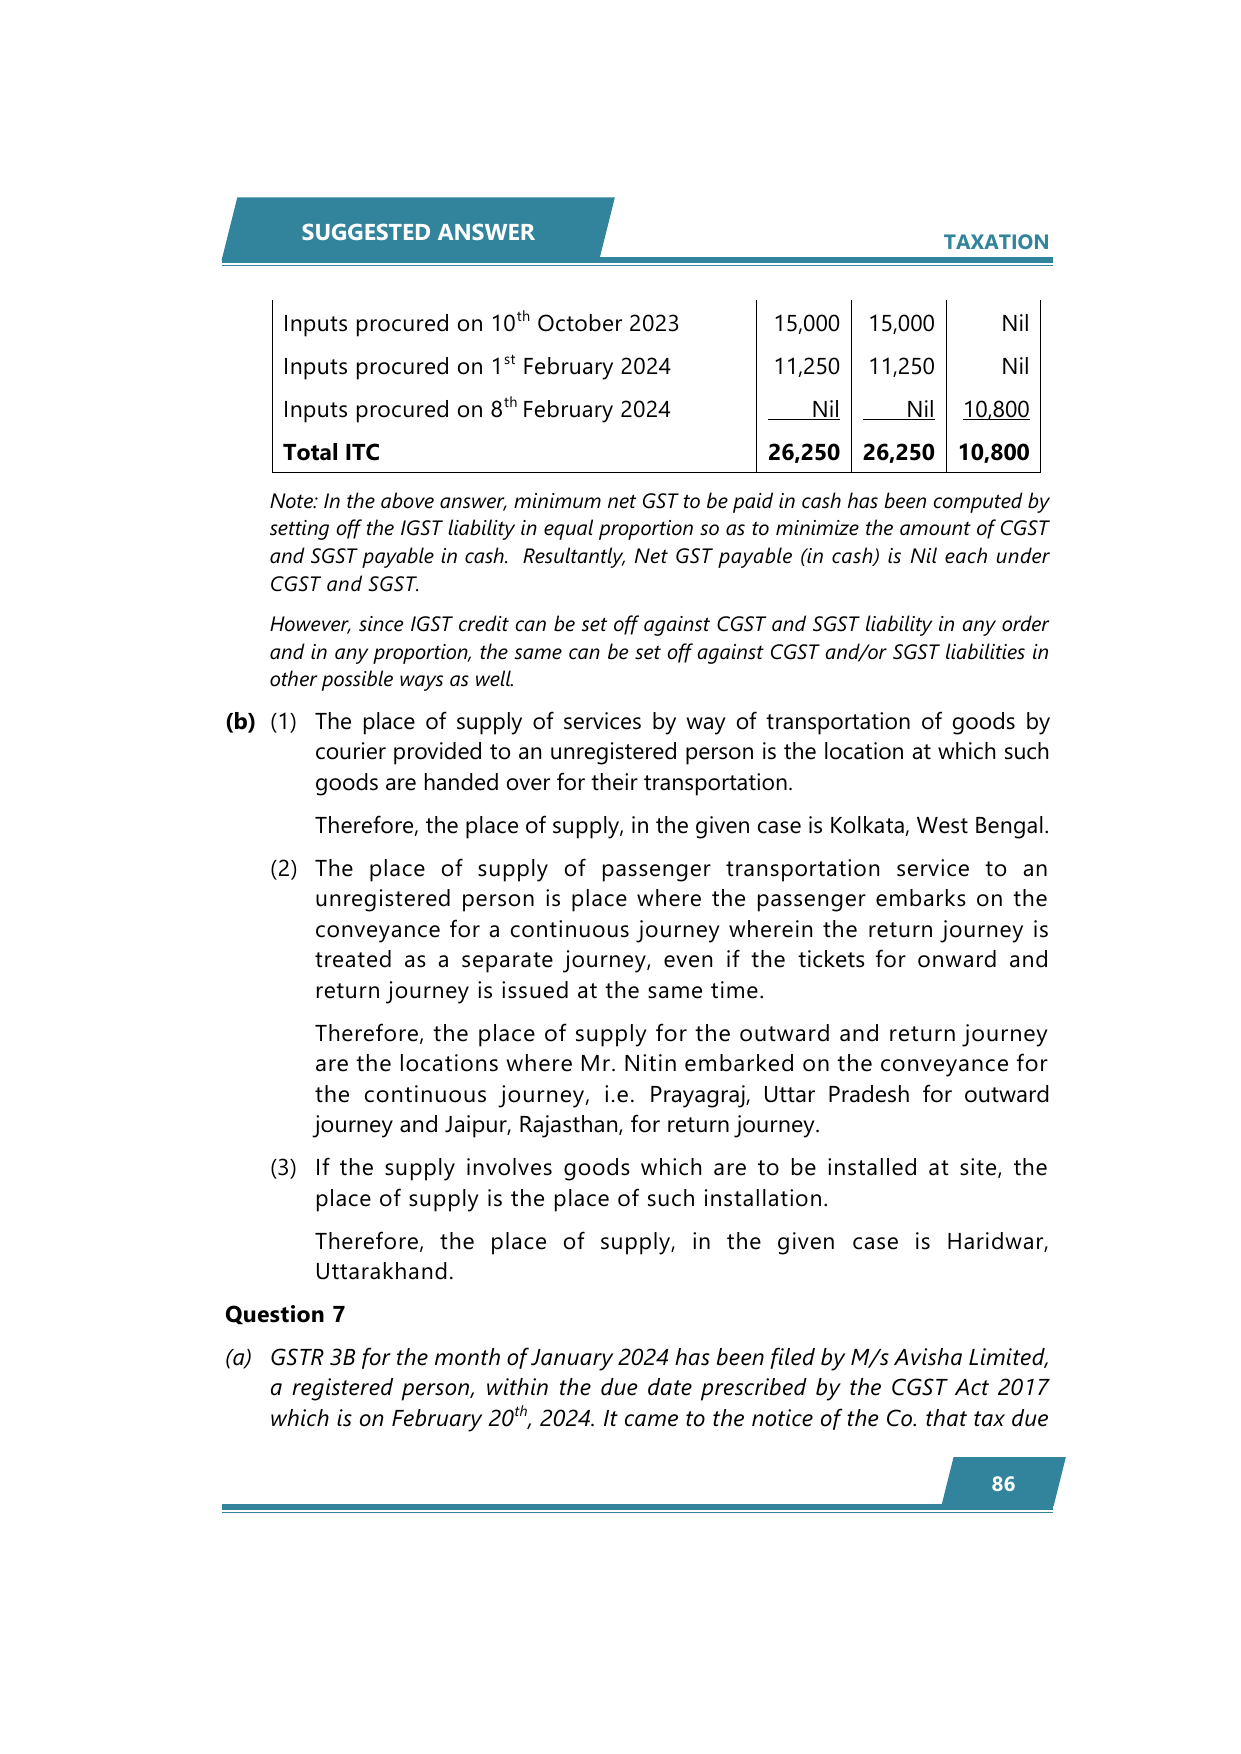
(a) As per the CGST Act 2017, Vishnu Limited was not mandatorily required to get registered, however it opted for voluntary registration and applied for registration on 12 thFebruary 2024. Registration certificate has been granted by the Department on 24 th February 2024, Vishnu Limited is not engaged in making inter-State outward taxable supplies. The CGST and SGST liability for the month of February, 2024 is ` 31,000 each. Vishnu Limited provides the following information of goods held in stock…
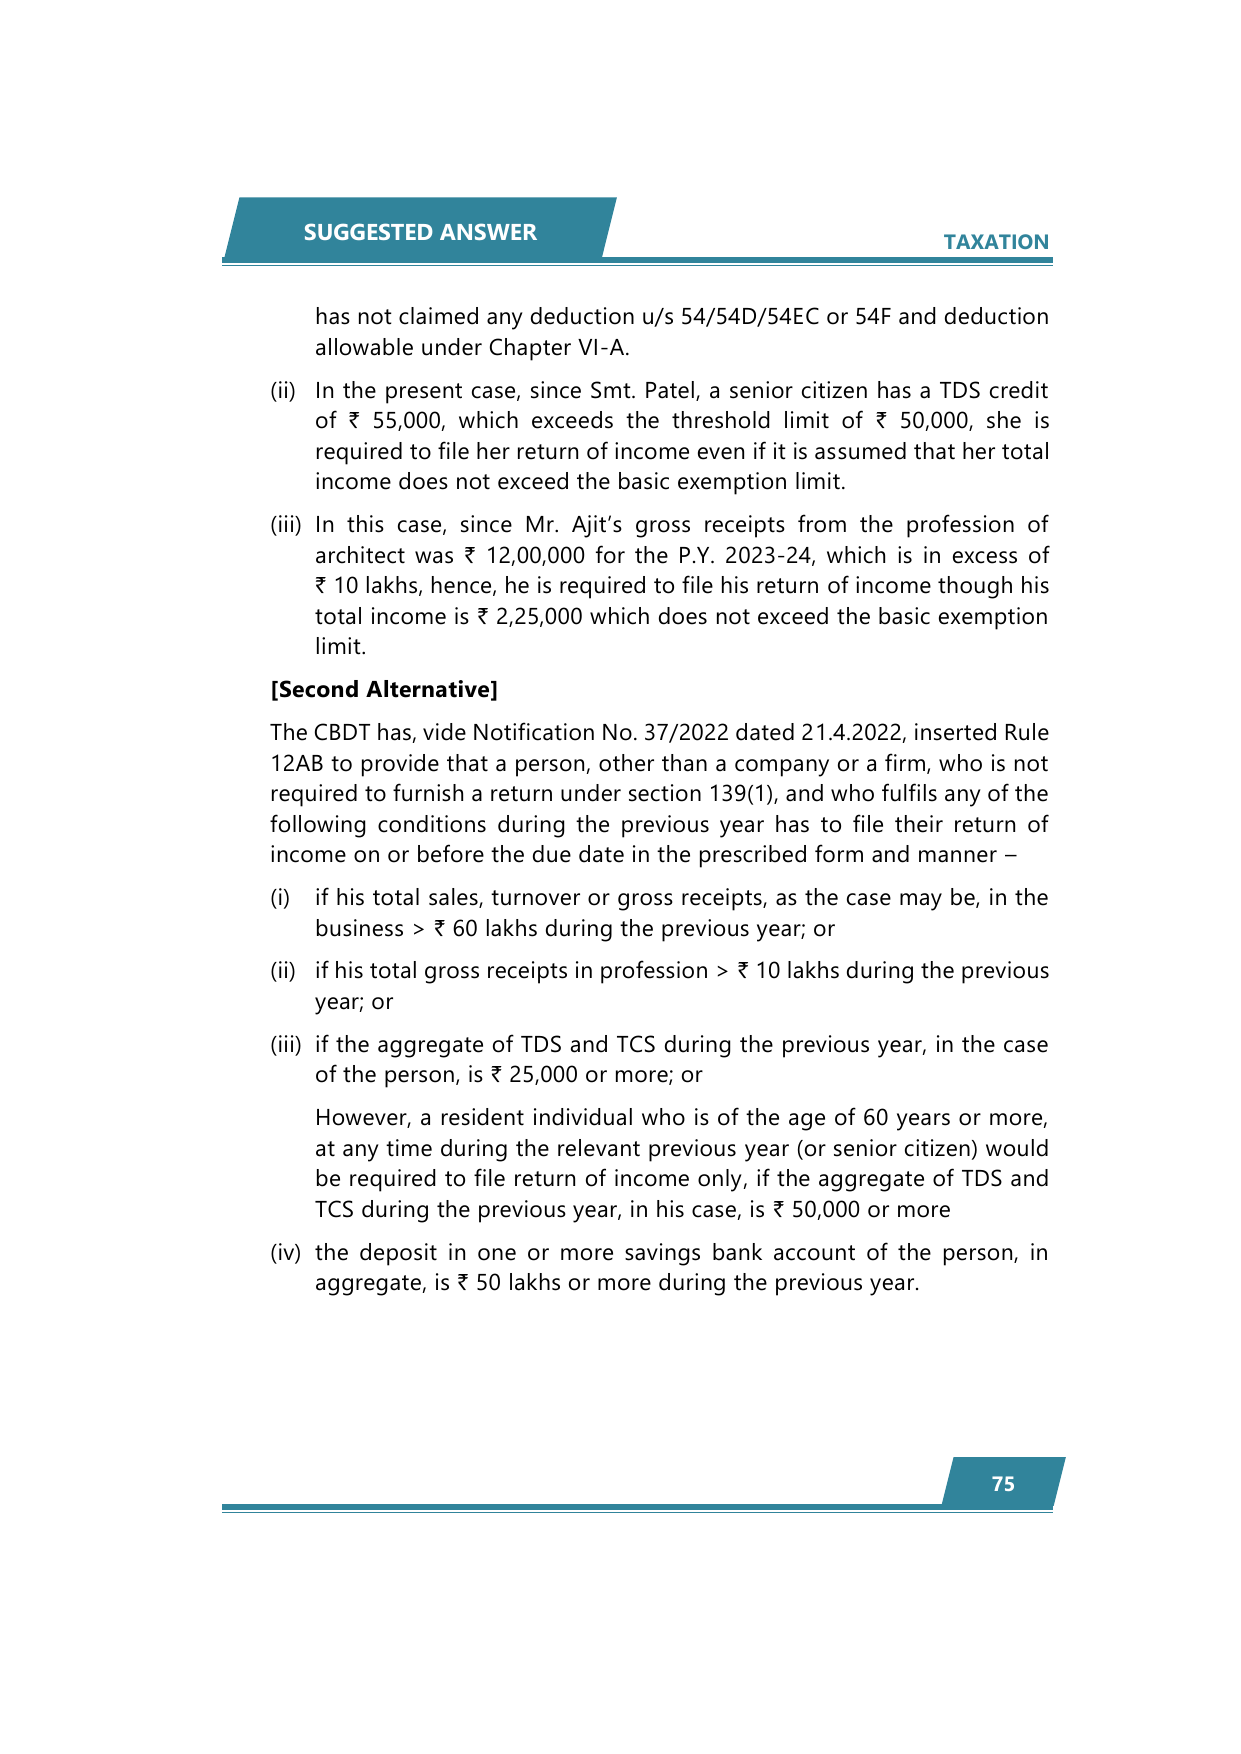
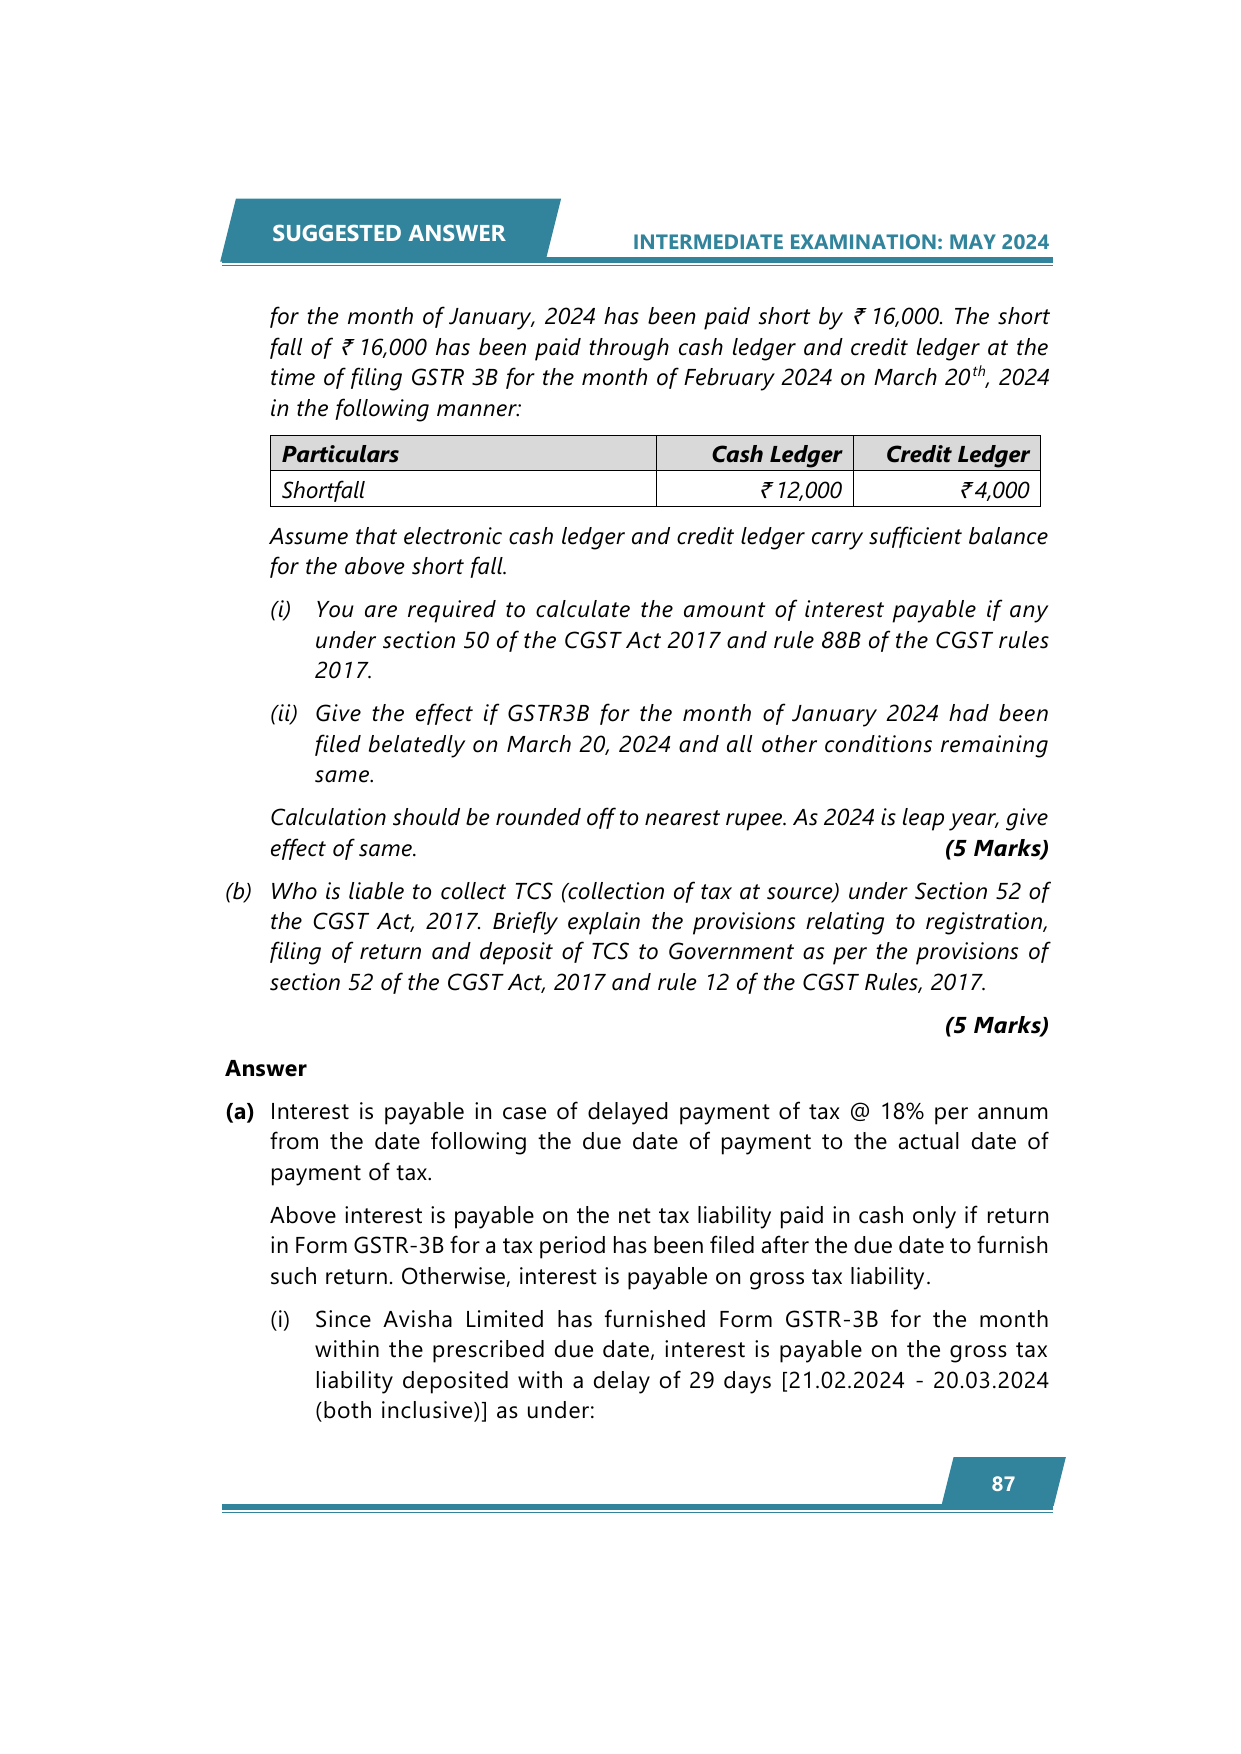
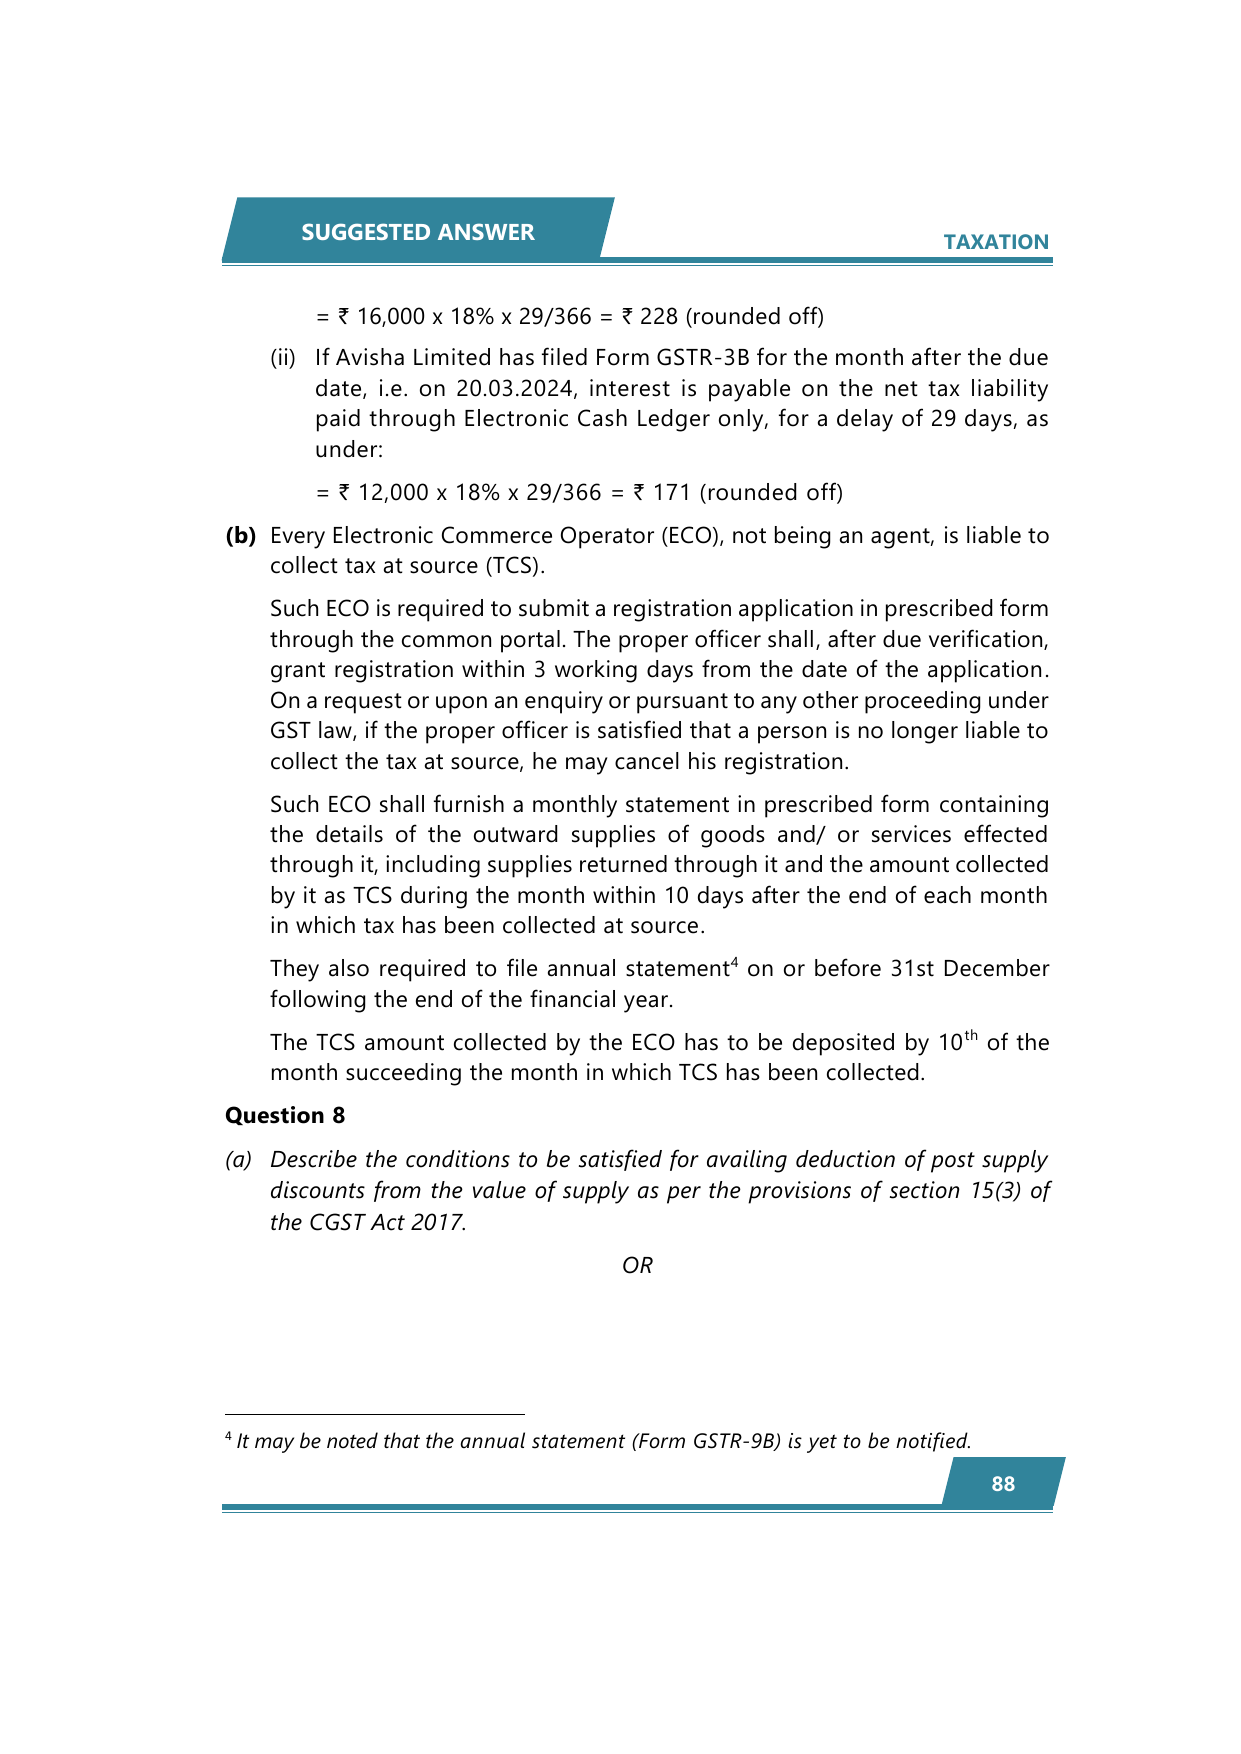
(a) GSTR 3B for the month of January 2024 has been filed by M/s Avisha Limited, a registered person, within the due date prescribed by the CGST Act 2017 which is on February 20 th, 2024. It came to the notice of the Co. that tax due 86 INTERMEDIATE EXAMINATION: MAY 2024 for the month of January, 2024 has been paid short by ` 16,000. The short fall of ` 16,000 has been paid through cash ledger and credit ledger…
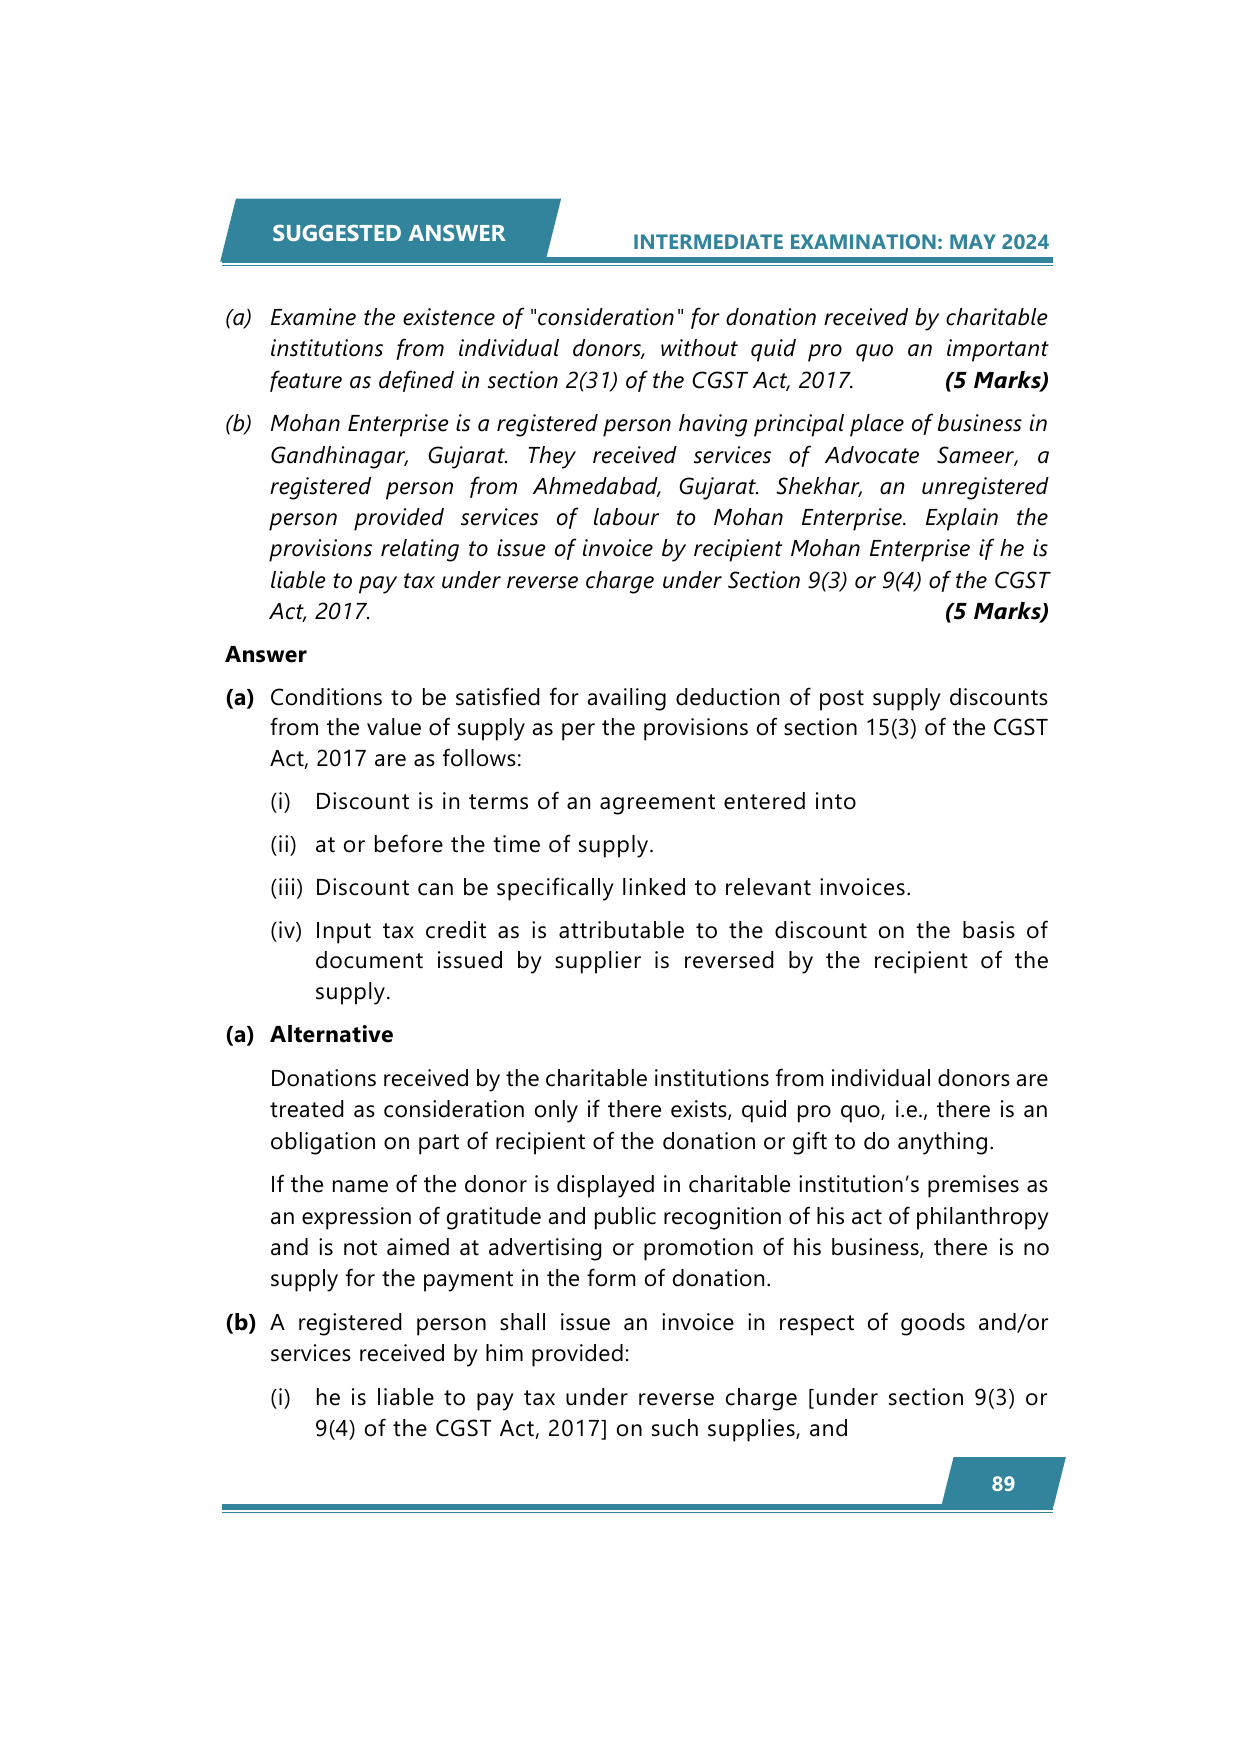
(a) Describe the conditions to be satisfied for availing deduction of post supply discounts from the value of supply as per the provisions of section 15(3) of the CGST Act 2017. 4 It may be noted that the annual statement (Form GSTR-9B) is yet to be notified. 88 INTERMEDIATE EXAMINATION: MAY 2024 (a) Examine the existence of "consideration" for donation received by charitable institutions from individual donors, without quid pro quo an important feature as defined in section 2(31) of…
Question previews auto-extracted from the official ICAI paper. Full scanned pages below.
Practice Taxation MCQs — free
Reinforce this paper with chapter-wise multiple-choice questions for CA Inter Taxation, based on the ICAI Study Material.
Questions with Suggested Answers


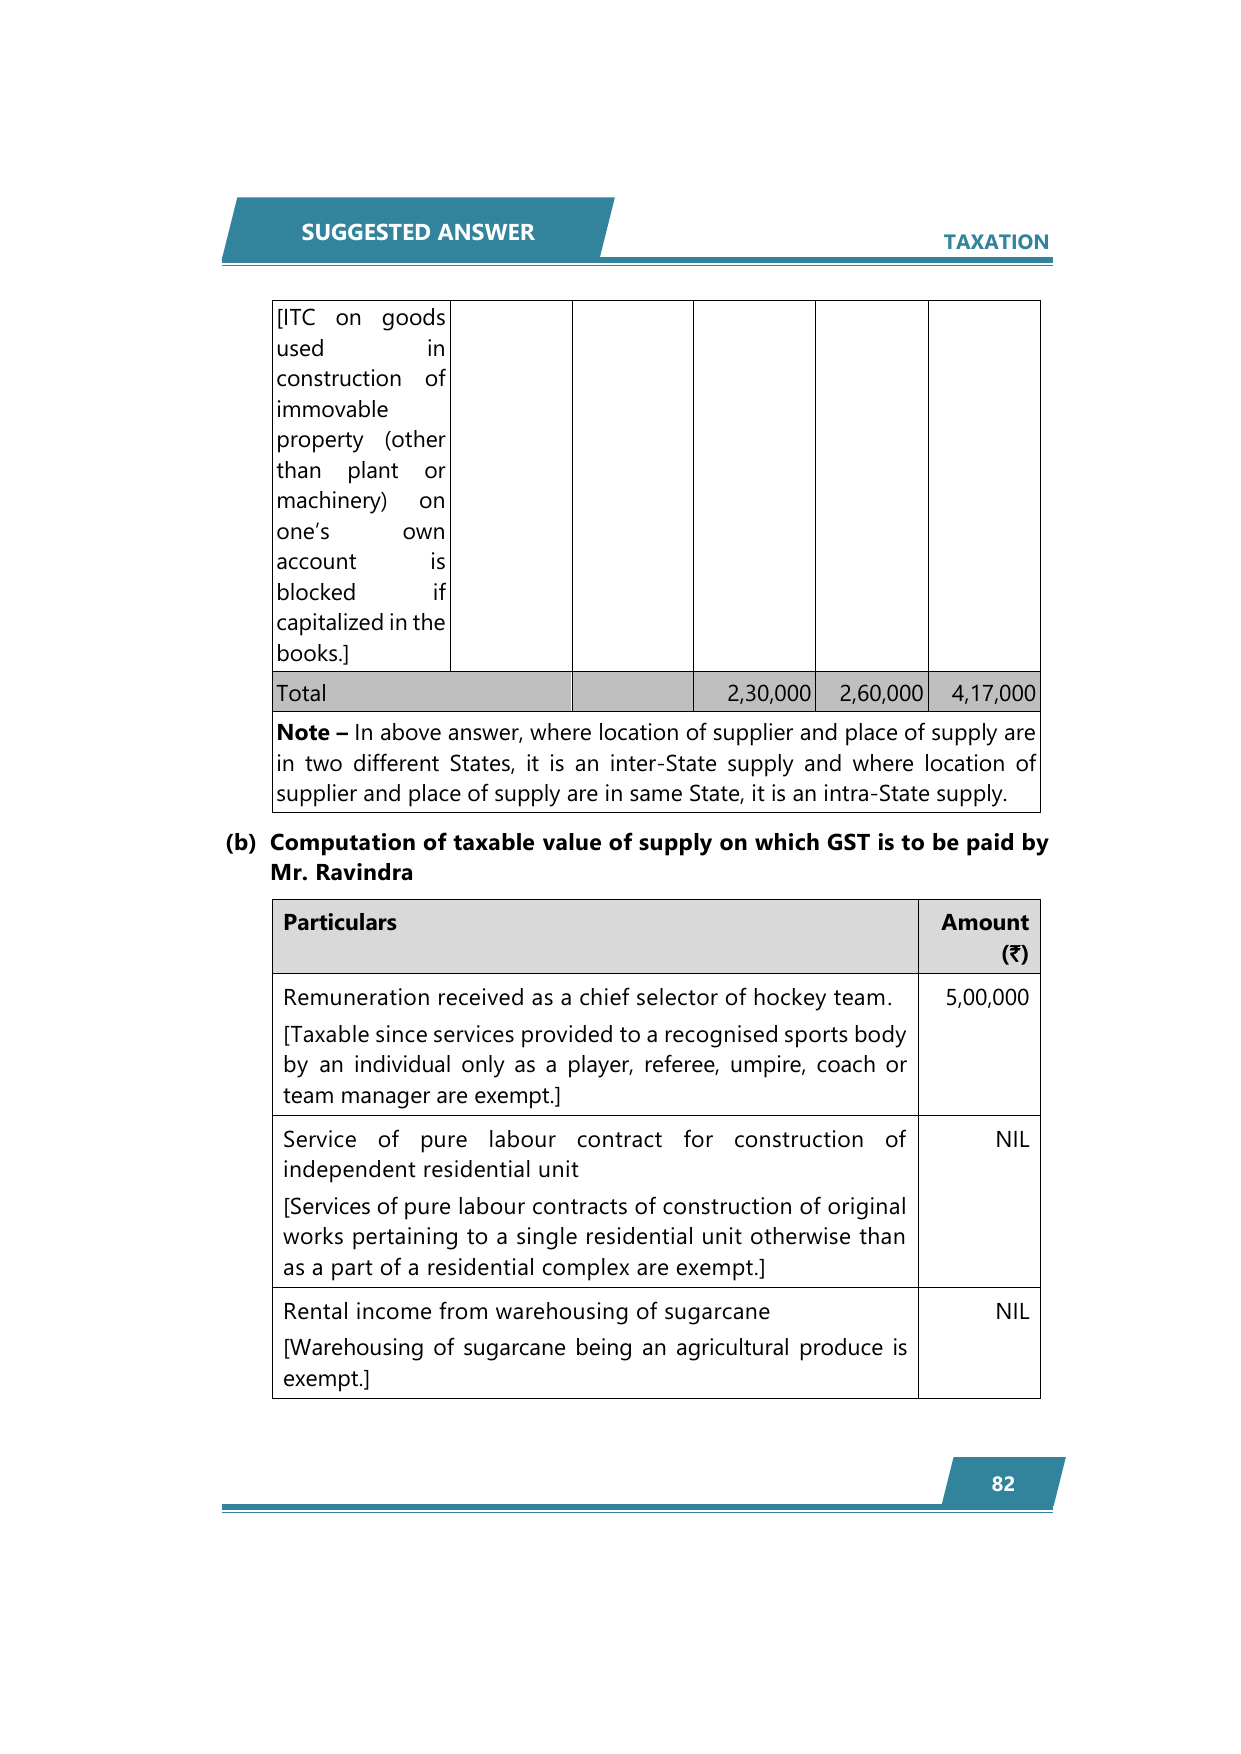
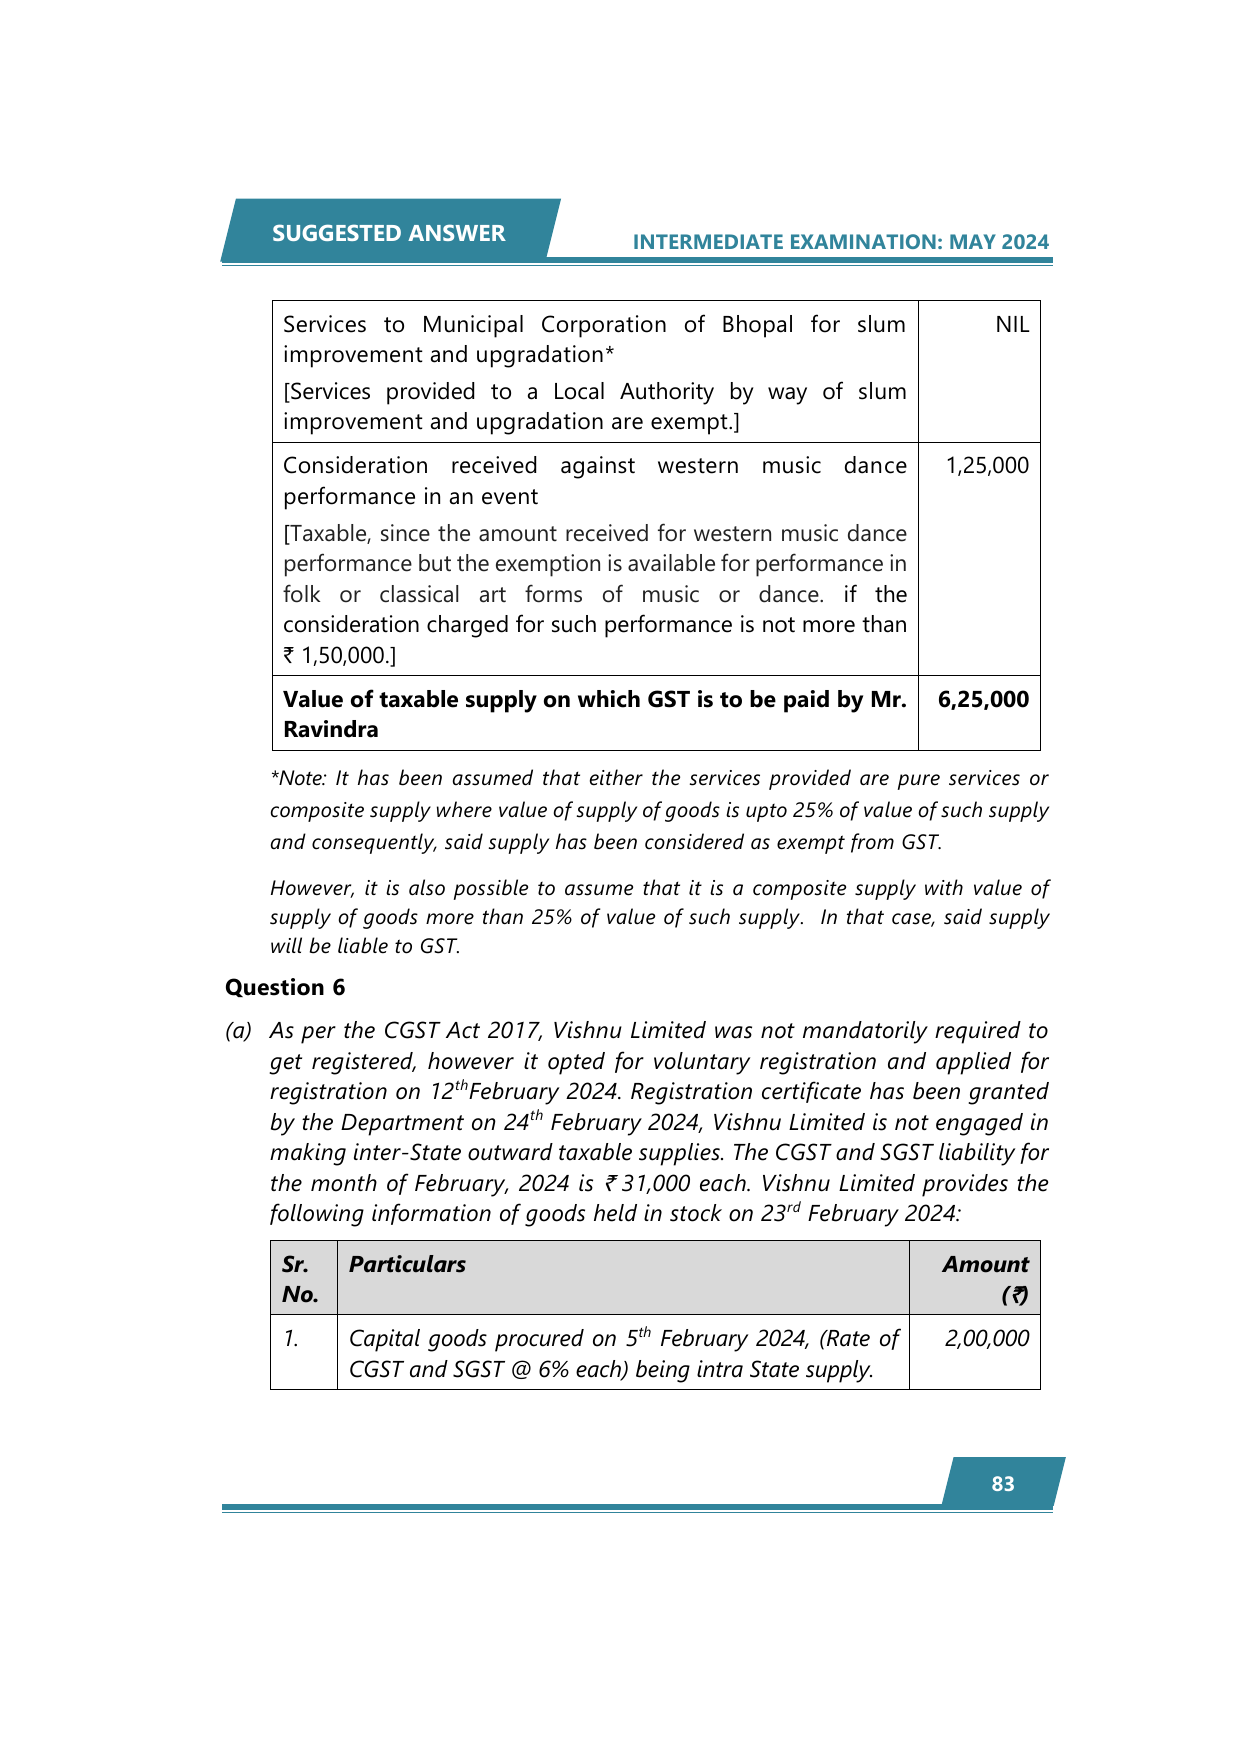
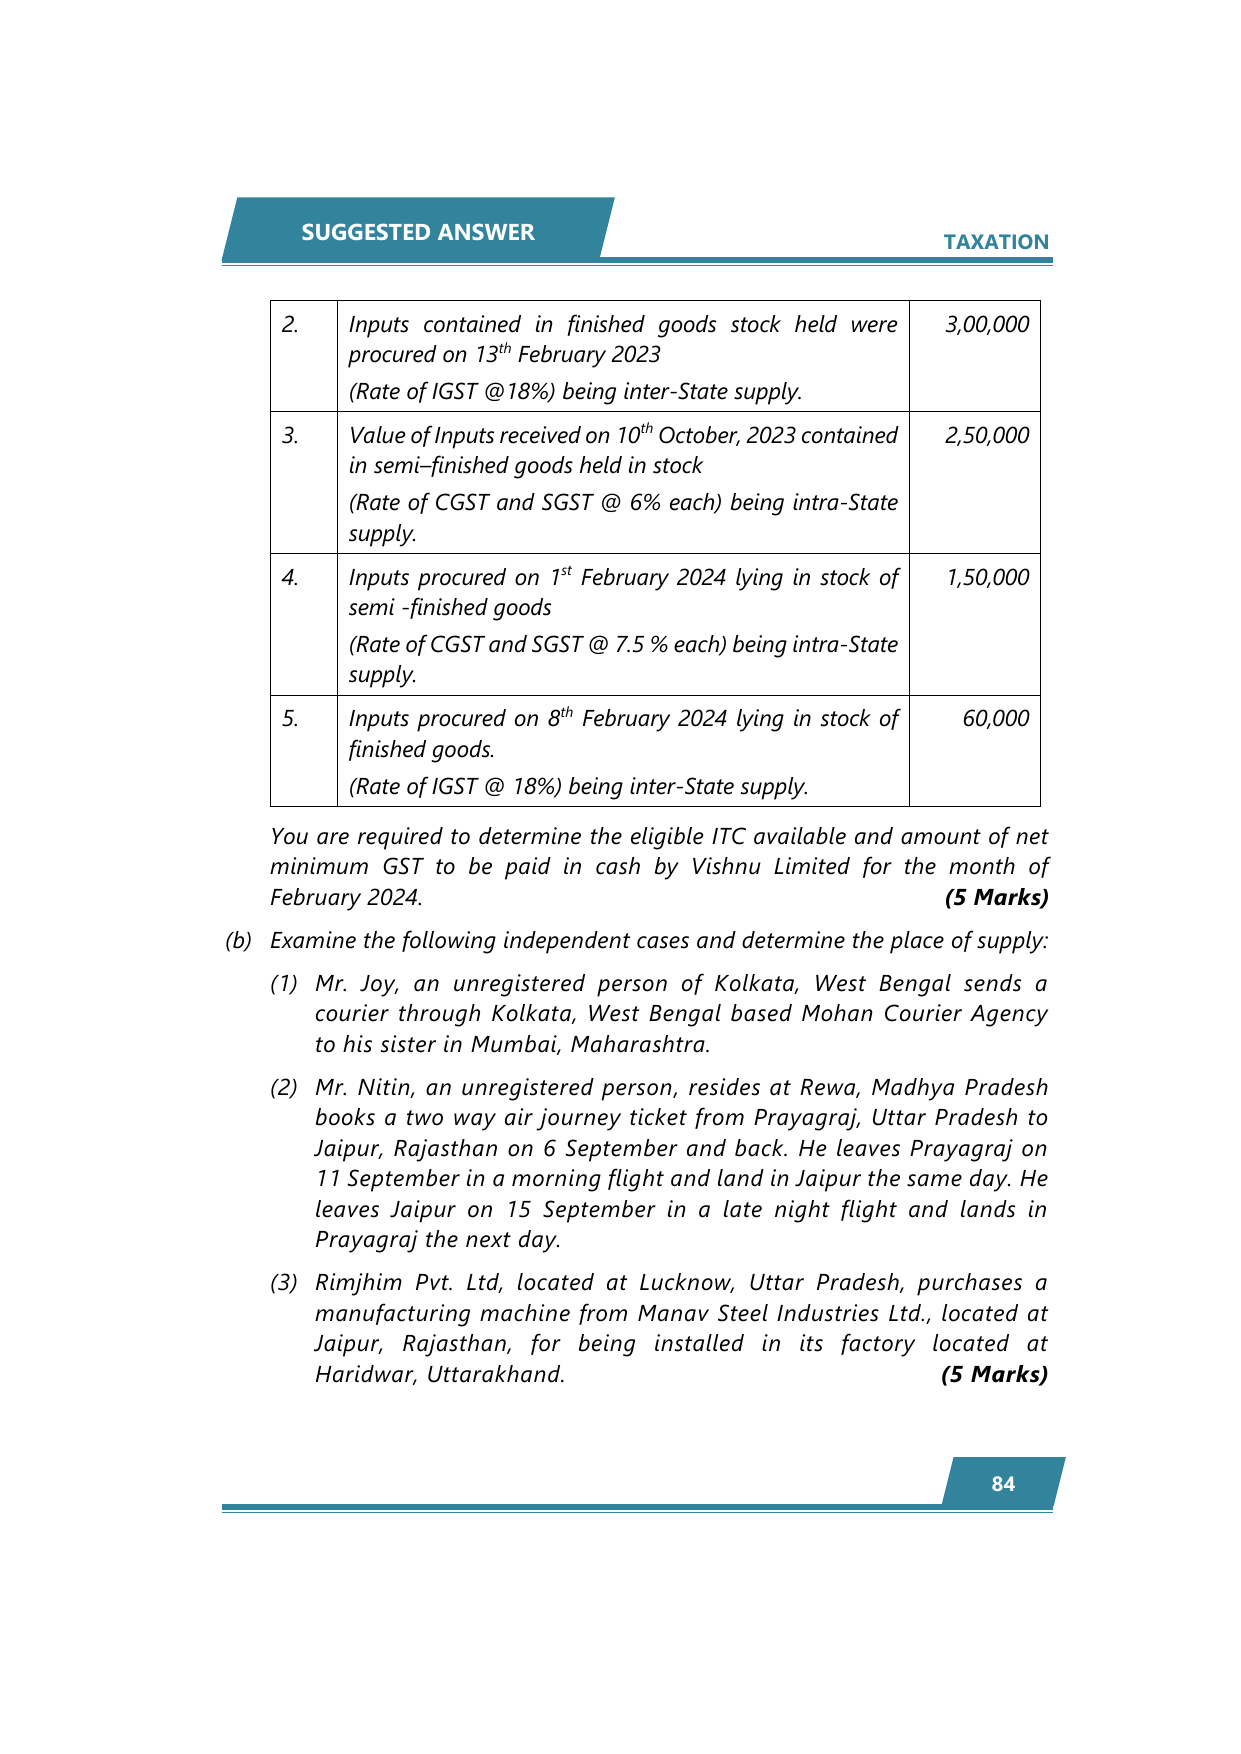
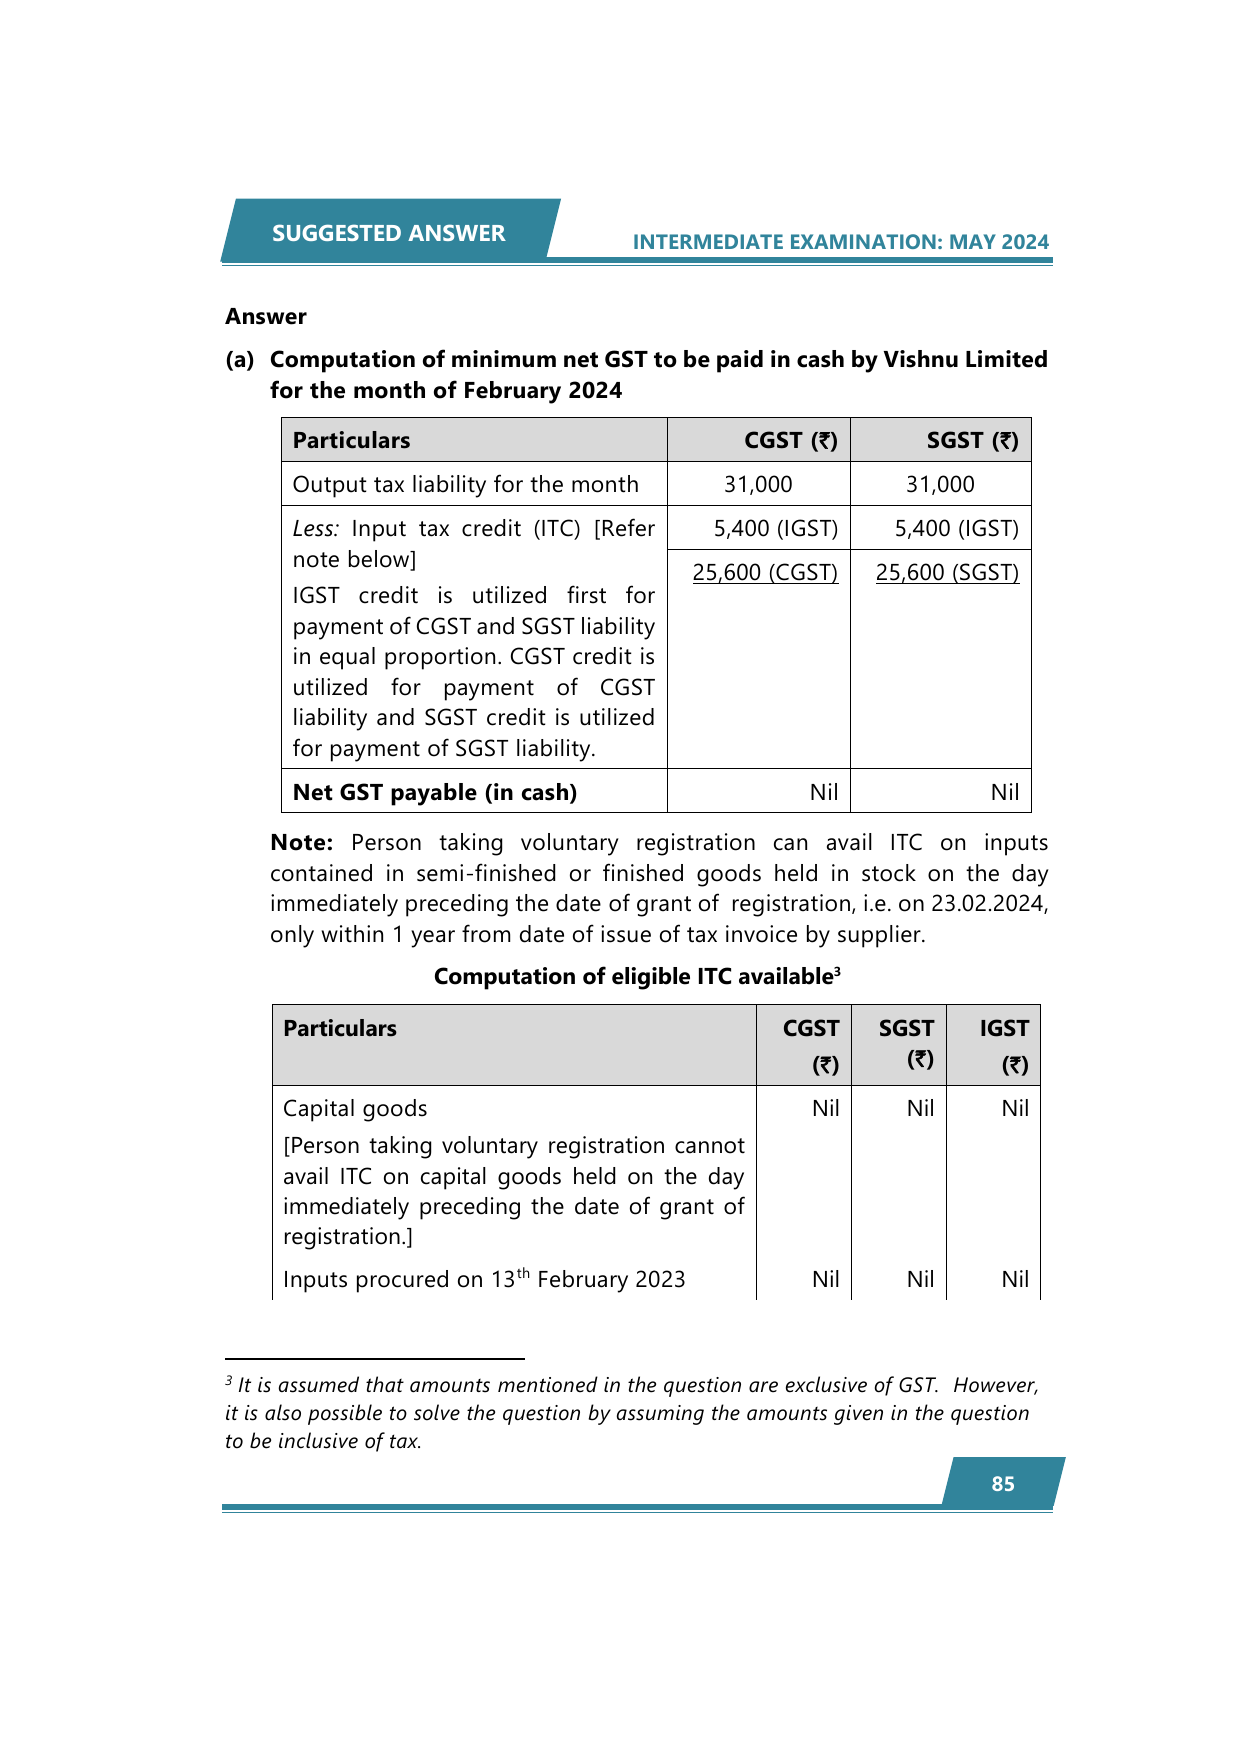
Questions with Suggested Answers
Answer
Answer not available
Related Papers
Get Notified About New Papers